

Car Insurance Rates by State: 6 Easy Ways to Pay Less
A friend moves two states over and suddenly her car insurance bill drops by half. Same car. Same clean record. Same coverage. Meanwhile someone else moves the other way and wonders what they did wrong.
Are you paying too much for car insurance?
Pick your state and enter what you pay each month to compare with the 2026 average.
They didn’t do anything wrong. Car insurance rates by state can differ by hundreds of dollars a year because each state has its own laws and weather and repair costs and lawsuit habits. This guide shows the latest averages for every state and explains why your state lands where it does. Then it shows what you can do about it.
The quick answer
As of fall 2026 the national average is about $187 a month for full coverage and about $99 a month for liability only according to Insurify. Maryland and Rhode Island are among the most expensive states. New Hampshire and Wyoming are among the cheapest. Your own price can be far from these averages.
Most and least expensive states
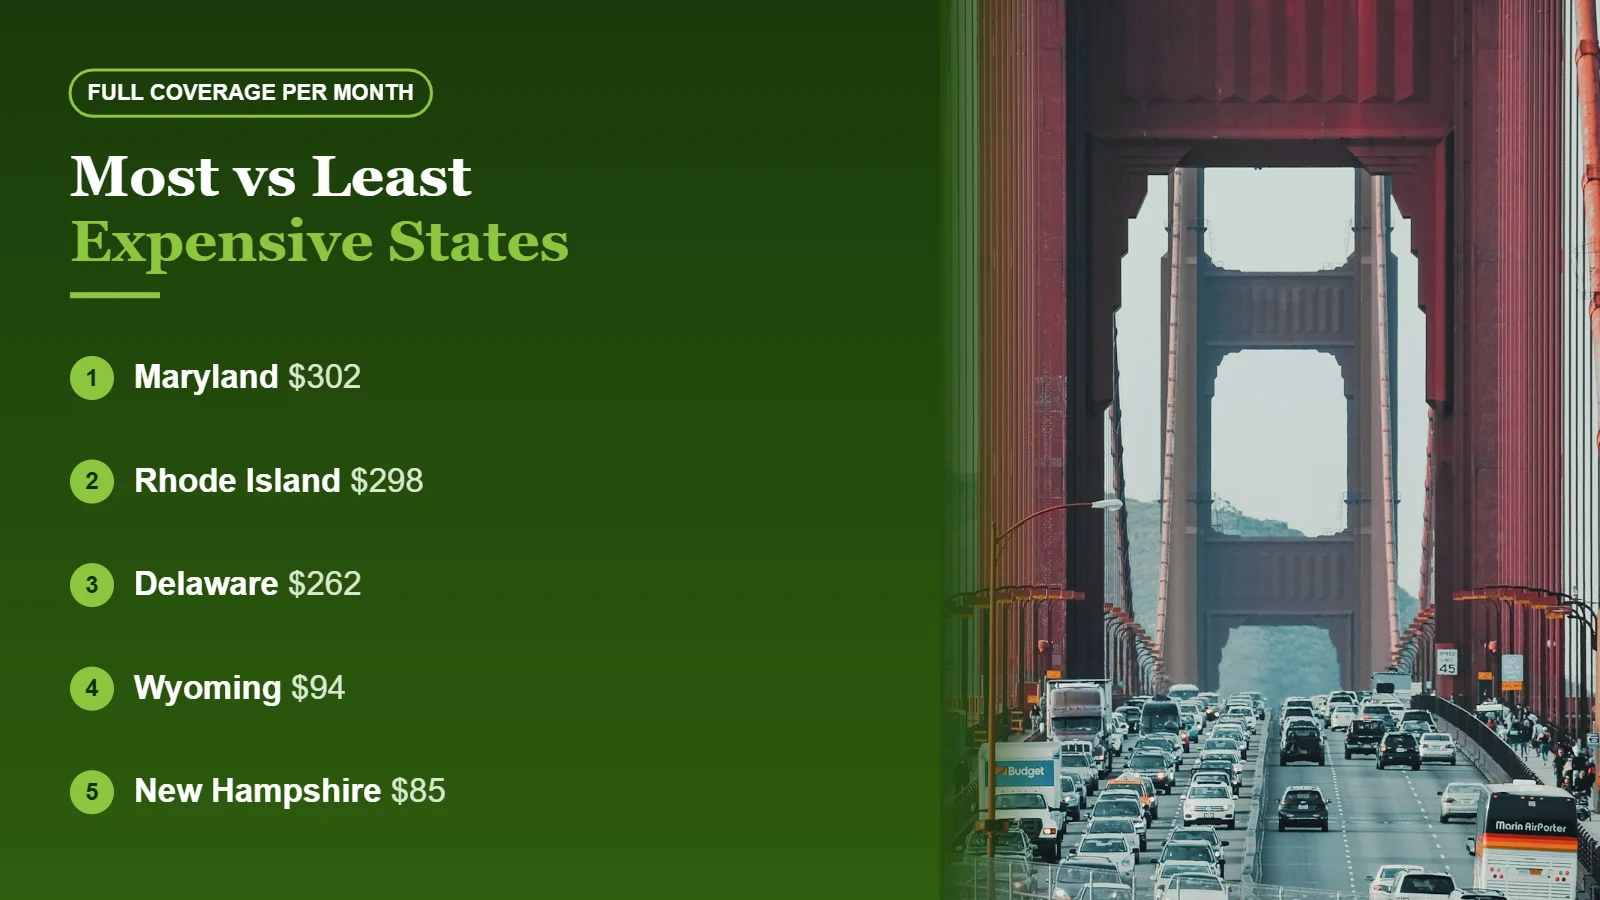
Full coverage usually means liability plus collision and comprehensive. Liability only covers damage and injuries you cause to other people. Here are the extremes based on recent Insurify data.
| State | Full coverage per month | Group |
|---|---|---|
| Maryland | $302 | Most expensive |
| Rhode Island | $298 | Most expensive |
| Delaware | $262 | Most expensive |
| Nevada | $260 | Most expensive |
| Georgia | $259 | Most expensive |
| New Hampshire | $85 | Cheapest |
| Wyoming | $94 | Cheapest |
| Idaho | $107 | Cheapest |
| Iowa | $111 | Cheapest |
| North Carolina | $113 | Cheapest |
Car insurance rates by state: full table
Find your state below. These are average monthly costs and Alaska is left out because the source didn’t have enough data for it.
| State | Full coverage | Liability only |
|---|---|---|
| Alabama | $142 | $66 |
| Arizona | $162 | $91 |
| Arkansas | $150 | $73 |
| California | $203 | $98 |
| Colorado | $217 | $97 |
| Connecticut | $225 | $162 |
| Delaware | $262 | $166 |
| Florida | $236 | $142 |
| Georgia | $259 | $157 |
| Hawaii | $126 | $62 |
| Idaho | $107 | $64 |
| Illinois | $162 | $84 |
| Indiana | $128 | $64 |
| Iowa | $111 | $56 |
| Kansas | $157 | $79 |
| Kentucky | $194 | $121 |
| Louisiana | $209 | $106 |
| Maine | $139 | $74 |
| Maryland | $302 | $191 |
| Massachusetts | $137 | $103 |
| Michigan | $229 | $130 |
| Minnesota | $182 | $93 |
| Mississippi | $186 | $89 |
| Missouri | $180 | $92 |
| Montana | $139 | $62 |
| Nebraska | $134 | $69 |
| Nevada | $260 | $164 |
| New Hampshire | $85 | $52 |
| New Jersey | $257 | $181 |
| New Mexico | $133 | $65 |
| New York | $218 | $145 |
| North Carolina | $113 | $69 |
| North Dakota | $114 | $66 |
| Ohio | $117 | $65 |
| Oklahoma | $169 | $83 |
| Oregon | $156 | $91 |
| Pennsylvania | $162 | $90 |
| Rhode Island | $298 | $177 |
| South Carolina | $255 | $160 |
| South Dakota | $152 | $62 |
| Tennessee | $132 | $60 |
| Texas | $204 | $110 |
| Utah | $146 | $92 |
| Vermont | $140 | $57 |
| Virginia | $207 | $118 |
| Washington | $184 | $95 |
| Washington DC | $237 | $136 |
| West Virginia | $156 | $83 |
| Wisconsin | $125 | $57 |
| Wyoming | $94 | $50 |
Why your state costs what it does
No single reason explains it. But a few factors show up again and again.
Lawsuits and legal rules. States where injury claims often end up in court tend to cost more. Florida and Georgia and South Carolina sit high on the list and legal costs are part of the story there.
Traffic and population. Crowded roads mean more crashes. That’s one reason states like New Jersey and Maryland and Delaware cost more than rural states.
Weather. Hail and flooding and hurricanes lead to comprehensive claims. Colorado’s hail storms help explain its high full coverage price.
Repair costs and theft. Modern cars are full of sensors and cameras. Even a small bumper repair can cost a lot. Areas with more car theft pay more too.
State minimums. Some states require more coverage than others. A higher required minimum means a higher starting price for everyone.
If you want the bigger picture behind price hikes our guide on why car insurance rates are rising goes deeper.
What’s happening with rates right now
Here’s some calmer news. Insurify reported that average costs fell about 6% in 2025 and expected rates to stay fairly stable in 2026. Prices held mostly steady through the summer. But it still projects small increases in 32 states by the end of the year with Connecticut and West Virginia near the top.
A few states may even see small drops. Insurify listed New Mexico and Arkansas and Minnesota and Colorado among them. So if you haven’t shopped in a while this is a decent time to look.
Regional patterns worth noticing
When you look at the full table a few patterns jump out. They won’t decide your price but they help explain it.
The Northeast corridor runs expensive. Maryland and Delaware and New Jersey and Rhode Island all sit near the top. Dense traffic and higher repair bills play a part. Interestingly New Hampshire right next door is the cheapest state of all.
The Southeast is mixed. Georgia and South Carolina and Florida are pricey. North Carolina and Tennessee are much cheaper. Neighboring states can feel like different worlds.
The rural Midwest and Mountain West are often cheaper. Iowa and Ohio and Wisconsin and Idaho and Wyoming land near the bottom. Fewer cars on the road usually means fewer crashes.
Weather can break the pattern. Colorado has a modest population compared with the coasts but hail pushes its full coverage price above many bigger states.
Full coverage or liability only
The table shows a big gap between the two columns. In many states full coverage costs nearly double. So it’s tempting to drop down to liability only. Sometimes that’s smart and sometimes it backfires.
If you have a car loan or lease your lender will almost always require full coverage. If your car is paid off and worth only a few thousand dollars then liability only can make sense. Ask yourself one question. If the car were totaled tomorrow could I replace it without borrowing money. If the honest answer is no then keep collision and comprehensive for now.
And don’t forget uninsured motorist coverage. Plenty of drivers on the road carry little or no insurance. This coverage protects you when one of them hits you and it’s usually cheap to add.
6 easy ways to pay less in any state
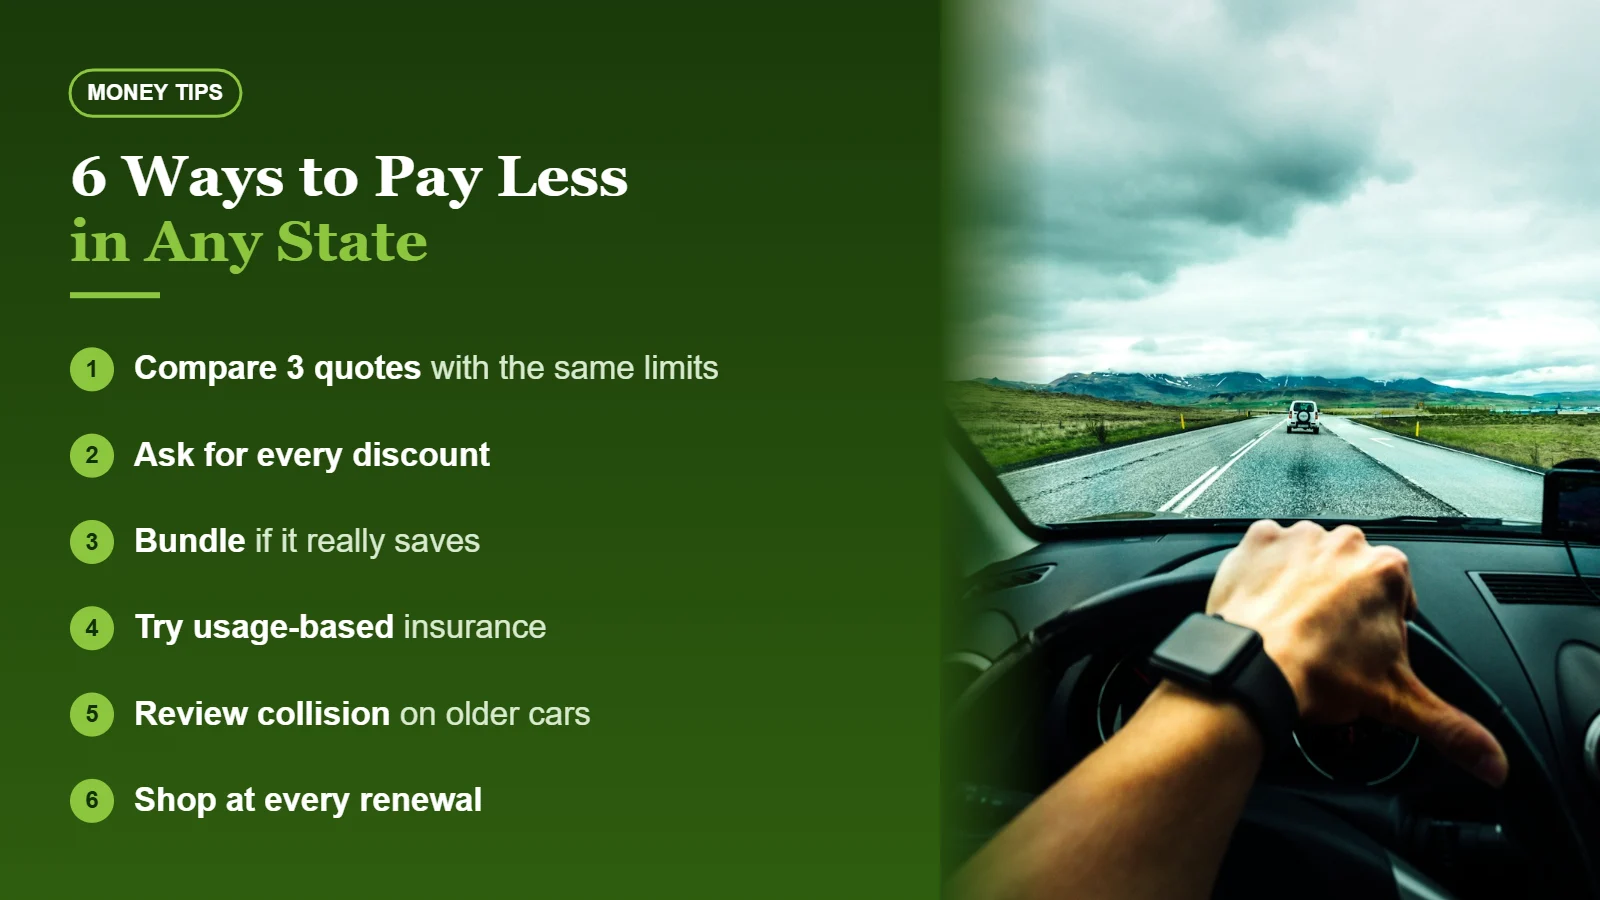
Way 1: Compare at least three quotes. Use the same liability limits and the same deductibles on each one. Otherwise the cheaper quote may just be weaker coverage.
Way 2: Ask for every discount. Good driver and good student and multi-car and paid-in-full and safety features all count. Many people never ask.
Way 3: Bundle if it really saves. Combining car with home or renters insurance can help. Our guide to bundling home and auto insurance shows how to test it.
Way 4: Try usage-based insurance if you drive carefully. An app or plug-in device tracks your driving and safe drivers can earn a discount. Read our breakdown of usage-based car insurance first.
Way 5: Review collision on older cars. If your car is worth very little the collision premium may not be worth paying. Check the car’s value before you drop it.
Way 6: Shop again at every renewal. Prices change even when nothing about you changes. Loyalty doesn’t always pay.
Moving to a new state
If you move you’ll usually need a policy that meets your new state’s rules. Many states expect you to update coverage soon after you register the car there. Call your insurer before the move and ask how the price will change. Sometimes it’s a nice surprise. Sometimes it’s a shock. Either way it’s better to know before you sign a lease.
Your state insurance department lists the minimum coverage rules. The NAIC links to every one of them.
Common mistakes
- Treating the state average as your price
- Buying only the state minimum in an expensive lawsuit state
- Comparing quotes with different limits
- Forgetting to update coverage after moving
- Never asking about discounts
That second point matters most. In a high-cost state a serious crash can blow past low minimum limits fast. Extra liability coverage often costs less than people expect.
Frequently asked questions
Which state has the cheapest car insurance
In recent Insurify data New Hampshire and Wyoming were among the cheapest with full coverage under $100 a month on average.
Which state has the most expensive car insurance
Maryland and Rhode Island topped the list at roughly $300 a month for full coverage on average.
Why is my quote higher than my state average
Your age and driving record and ZIP code and car and credit history in most states all affect the price. Averages hide those differences.
Final thoughts
You can’t change your state’s laws or weather. But you can change how you shop. Compare honestly and ask for discounts and review coverage once a year. That’s usually where the real savings hide.
For help choosing a company see our best car insurance policy guide. Parents adding a new driver can also read about car insurance for teenage drivers.
Disclaimer: This article is general information and not advice for your exact situation. Averages come from third-party data and real quotes vary by driver and insurer and ZIP code. Check current details with a licensed agent or your state insurance department.