

Florida Home Insurance Rates Are Dropping
For years the renewal letter was the scariest piece of mail a Florida homeowner could get. Double-digit increases. Non-renewal notices. Insurers packing up and leaving the state. A lot of people simply got used to bad news.
So here’s something that feels strange to write. Florida home insurance rates are actually coming down for a lot of people right now. Not for everyone and not by a huge amount in every case. But the direction has changed. This guide explains who is getting the cuts and why it’s happening and what you can do so your own bill drops too.
The quick answer
Florida regulators have approved rate decreases for dozens of home insurers over the past two years. In October 2026 alone the state announced cuts of up to 12.1% that affect more than 824,000 policyholders. Cuts usually show up at renewal. They don’t happen automatically for everyone so it pays to check your renewal and shop if your rate didn’t move.
What the latest Florida home insurance rate cuts look like
On October 29, 2026 the Florida Office of Insurance Regulation listed a new round of approved decreases. Here are a few of them as reported by local news.
| Insurer | Policy types | Average cut | Policyholders |
|---|---|---|---|
| Universal P&C | HO3, HO4, HO6, HO8 | 5% | 512,000 |
| Kin Insurance | HO3 | 3.4% | 99,800 |
| Cypress P&C | HO3, HO6 | 12.1% | 64,300 |
| Castle Key Indemnity | HO6 | 12% | 51,580 |
| Security First | HO6 | 7.3% | 17,300 |
HO3 is a standard homeowners policy. HO6 covers condo owners. HO4 is renters insurance. So these cuts reach houses and condos and some renters too.
The state also says more decreases are pending for November through January. Those could reach roughly 450,000 more Floridians. And back in September other insurers such as Vyrd and One Alliance got cuts of about 10%.
Citizens policyholders too
Citizens Property Insurance is the state-backed insurer of last resort. Earlier in 2026 Florida announced an average Citizens cut of 8.7% at renewal. South Florida saw the biggest drops. Broward and Miami-Dade averaged around 14%.
Why rates are finally falling
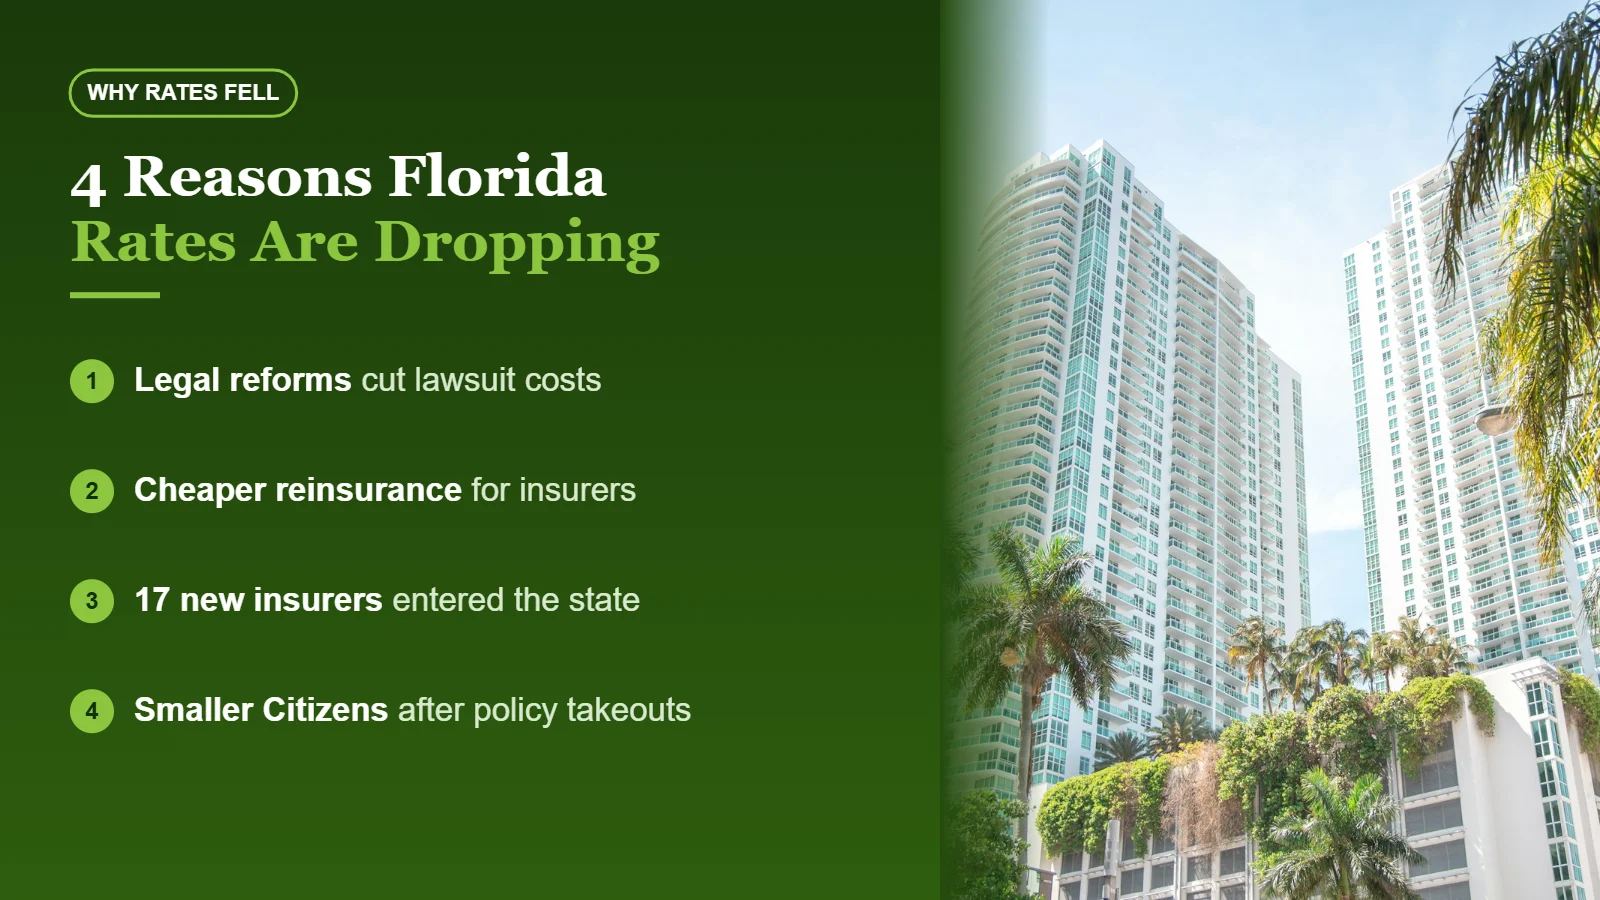
Honestly it’s not because hurricanes got smaller. It’s mostly about lawsuits and the cost of insurance for insurers.
Legal reforms. Florida passed big insurance laws in 2022 and 2023. They ended one-way attorney fees and cut down on abuse of assignment of benefits. Before that Florida had a huge share of the country’s homeowners claim lawsuits. Fewer lawsuits mean lower costs for insurers.
Cheaper reinsurance. Reinsurance is insurance that insurance companies buy for themselves. Its price dropped and Florida insurers pass some of that saving on.
More competition. State officials say 17 new insurers have entered Florida since the reforms. More companies fighting for customers usually means better prices.
Smaller Citizens. Hundreds of thousands of policies moved from Citizens back to private companies. That lowers the risk that everyone ends up paying for a bad storm season.
The honest catch
A 5% cut on a very high bill still leaves a high bill. Florida remains one of the most expensive states for home insurance. And a rate cut is not the same as your personal premium going down.
Your premium can still rise if your home’s rebuild cost went up or your roof got older or you filed a claim. The cut applies to the insurer’s base rates. Everything else about your house still counts. If your roof is part of the problem then our guide on how roof age affects your home insurance explains why.
How to make sure you actually pay less
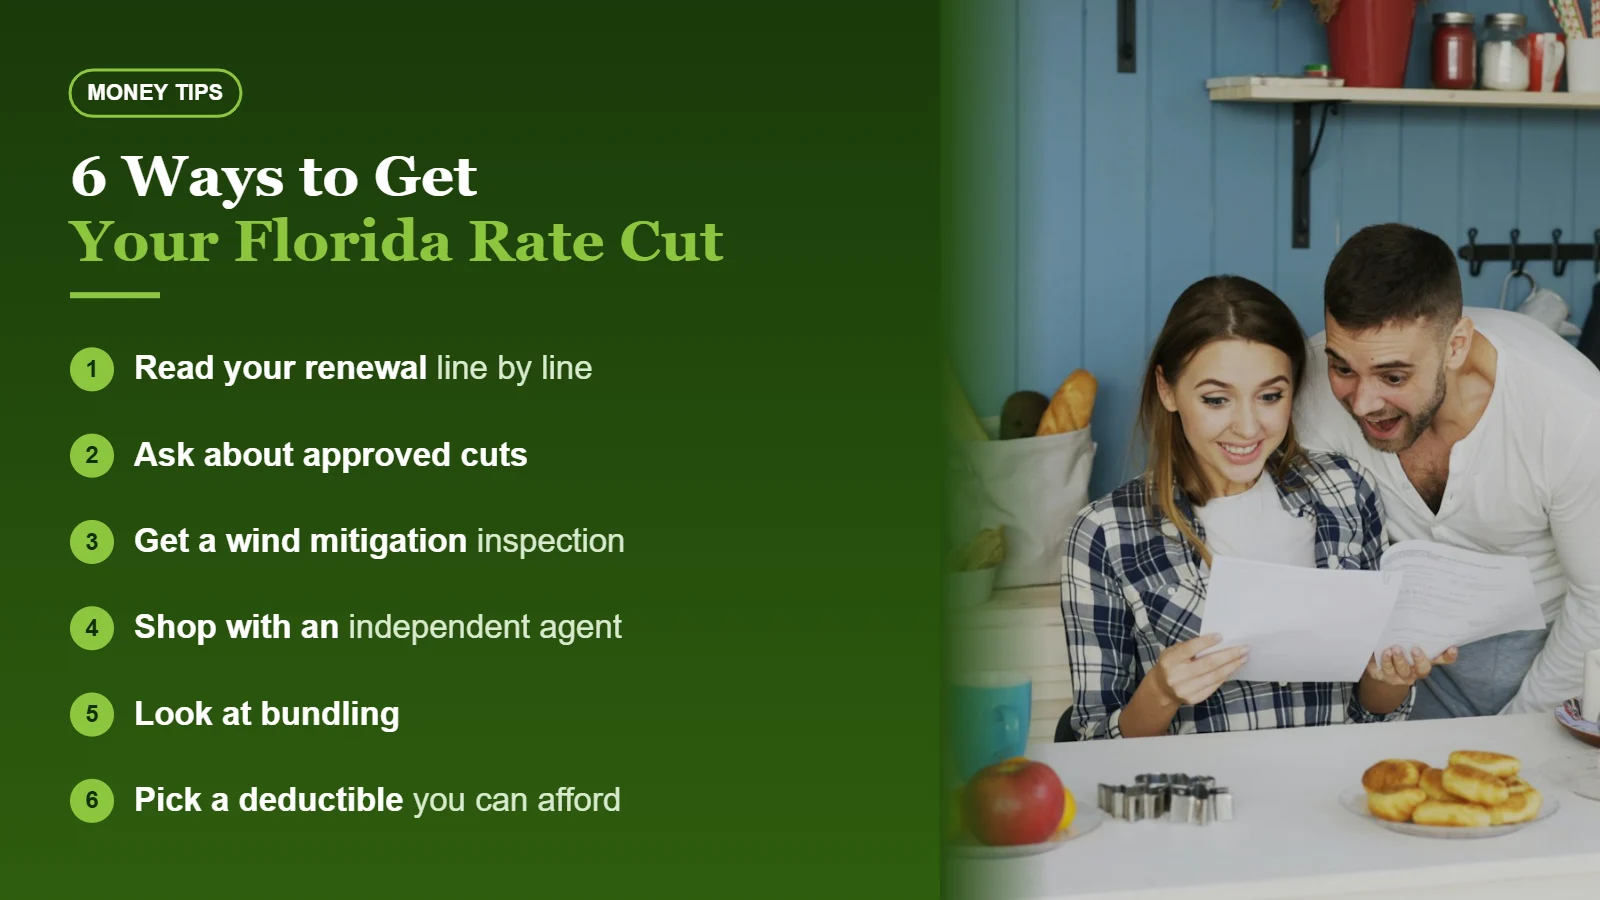
Step 1: Read your renewal line by line. Compare this year’s premium with last year’s. Look at the dwelling coverage amount and the hurricane deductible. If the price went up check whether coverage went up too.
Step 2: Ask your insurer about approved cuts. Call and ask a simple question. Did you file a rate decrease this year and does it apply to my policy at renewal. You’d be surprised how often people never ask.
Step 3: Get a wind mitigation inspection. Florida insurers must offer discounts for features that help a home stand up to wind. Think roof straps and impact windows and shutters and roof shape. A licensed inspector fills out a short form and many homeowners see real savings after it’s on file. Check whether the state’s My Safe Florida Home program is open in your area since it has offered free inspections in the past.
Step 4: Shop with an independent agent. New insurers are writing policies again. An independent agent can quote several of them at once. Compare the same coverage amounts and the same hurricane deductible or the comparison won’t mean much.
Step 5: Look at bundling. Some Florida auto insurers cut rates in 2026 too. Bundling home and car can help. Our guide to bundling home and auto insurance shows when it’s worth it.
Step 6: Think carefully about your deductible. A higher hurricane deductible lowers the premium. But only choose an amount you could really pay after a storm.
If you’re still with Citizens
You may get a takeout offer. That’s when a private insurer offers to take over your policy. Don’t accept or reject it on reflex. Compare the price and coverage side by side with your Citizens renewal. Sometimes it’s a good deal. Sometimes the coverage is thinner.
If you got a non-renewal notice instead then our guide on the homeowners insurance non-renewal crisis walks through your next steps.
Real situations and what usually fits
A condo owner in Broward. HO6 policies saw some of the biggest cuts this year. If your renewal didn’t drop it’s a good moment to compare.
An older home with an original roof. Rate cuts may not offset roof-related surcharges. A roof update plus a wind mitigation form often matters more than any statewide cut.
A first-time buyer. Get quotes before you close and not after. Our guide for first-time homebuyers has the timeline.
Questions to ask your agent this season
A short phone call can save you real money. Keep these questions next to you when you call so you don’t forget the important ones.
- Has my insurer filed a rate decrease and when does it apply to me
- Is my wind mitigation form on file and is it still current
- What would my premium be with a different hurricane deductible
- Which newer insurers are writing policies in my county right now
- Does my dwelling coverage still match today’s rebuild cost
That last question is easy to skip. But being underinsured after a storm can cost far more than any discount you’ll ever get. If the agent suggests raising dwelling coverage ask them to show you the rebuild estimate behind the number.
What this means for your budget
I’d treat any saving as a cushion and not as free money. Florida’s market can still turn fast after a big storm season. Some homeowners put the difference into an emergency fund for their hurricane deductible. That way the next storm doesn’t turn into a debt problem.
It’s also smart to set a calendar reminder about 45 days before your renewal date. That gives you enough time to get quotes and finish a wind mitigation inspection before the new price locks in.
Common mistakes to avoid
- Assuming a statewide cut lowers your bill without checking
- Comparing quotes with different hurricane deductibles
- Never filing a wind mitigation form
- Cutting dwelling coverage just to lower the price
- Ignoring flood risk because a standard policy doesn’t cover it
That last one matters a lot in Florida. A regular homeowners policy doesn’t cover flood damage. Flood insurance is a separate policy and it usually has a waiting period before it starts.
Frequently asked questions
Are Florida home insurance rates going down in 2026
For many insurers yes. Dozens have filed for decreases since 2024 and the state approved new cuts in October 2026. Your own bill depends on your home and your insurer.
When will I see the decrease
Usually at your next renewal or when you buy a new policy. Cuts don’t normally lower a bill in the middle of a policy term.
Does a wind mitigation inspection really help
It often does. Florida requires insurers to offer credits for wind-resistant features. The size of the discount depends on what your home has.
Final thoughts
After years of bad news this is a real shift. But the savings mostly go to people who check and ask and compare. Spend an hour on your renewal this season. It may be the easiest money you save all year.
For a wider view of choosing a policy see our best home insurance policy guide.
Disclaimer: This article is general information and not advice for your exact home. Rates and discounts vary by insurer and location and can change. Confirm details with a licensed Florida agent or the Florida Office of Insurance Regulation before you decide.