

10-Year Term Life Insurance: Is It Enough?
Most life insurance advice pushes you toward a 20 or 30 year policy. Then you see a 10-year quote and it’s noticeably cheaper. And a small voice asks the obvious question. Do I really need coverage for 30 years or am I paying for time I’ll never use?
You’re not the only one asking. Searches for 10-year term life insurance have jumped sharply in 2026 as people look for coverage that fits a tighter budget. This guide explains who a 10-year term really suits and who it can quietly hurt. It also covers what it costs and the one feature you should never skip.
The quick answer
10-year term life insurance is a good fit when your biggest money responsibility ends within about ten years. Think a mortgage close to payoff or kids who’ll be grown soon or a business loan. If your need lasts longer a 10-year policy can leave you buying new coverage later at an older age and a higher price.
What 10-year term life insurance actually is
Term life insurance pays a death benefit if you die during a set number of years. With a 10-year term that window is ten years. The premium is the amount you pay to keep the policy active. On most 10-year policies it stays level the whole time.
There’s no cash value and no investment part. If you outlive the term the policy simply ends. That’s why it’s cheap. You’re only paying for protection during the years you choose.
What it costs in 2026
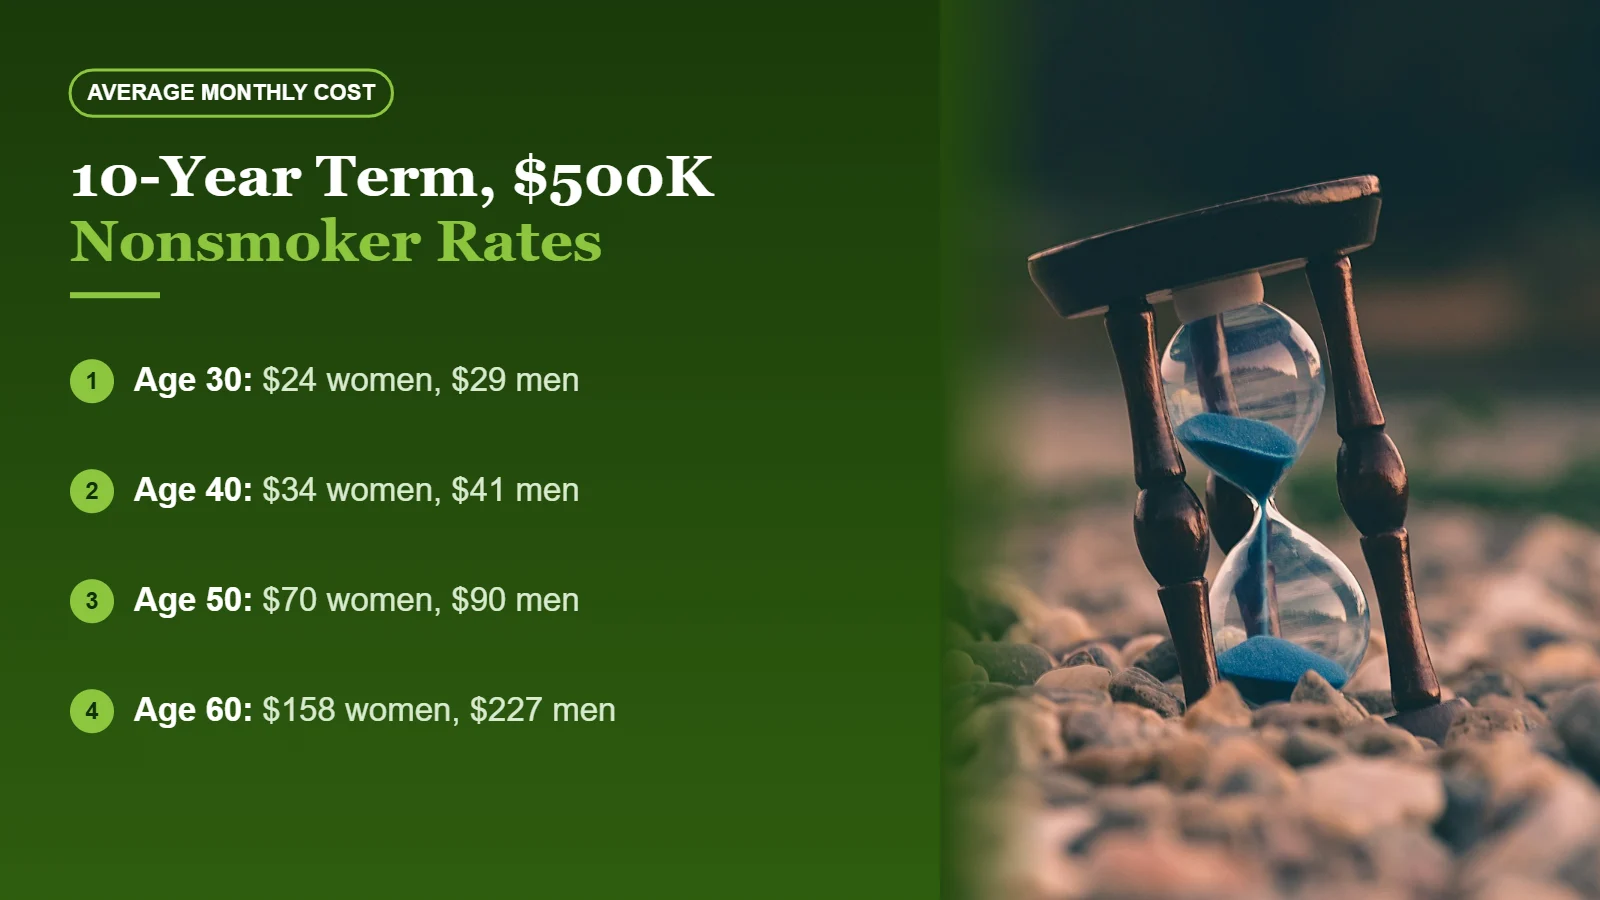
Prices depend on your age and health and gender and whether you smoke. Here are average monthly estimates from MoneyGeek for a $500,000 policy and a nonsmoker in average health.
| Age | Female | Male |
|---|---|---|
| 30 | $24 | $29 |
| 35 | $28 | $34 |
| 40 | $34 | $41 |
| 45 | $49 | $61 |
| 50 | $70 | $90 |
| 55 | $104 | $144 |
| 60 | $158 | $227 |
Notice the jump after 45. Rates climb faster each year you wait. That’s the hidden cost of buying short coverage now and needing more later.
And here’s how term length changes the price at age 35 for the same $500,000.
| Term length | Female | Male |
|---|---|---|
| 10-year | $28 | $34 |
| 20-year | $37 | $47 |
| 30-year | $65 | $80 |
The 20-year term costs only a bit more per month than the 10-year. For many young families that small gap buys ten extra years of protection. These are estimates so your own quote will be different.
Who a 10-year term really fits
- Someone with about ten years left on a mortgage
- Parents whose youngest child is already a teenager
- A person in their 50s bridging the years until retirement savings are enough
- A business owner covering a loan or a partner buyout for a short period
- Anyone adding a small extra layer on top of a longer policy
That last one is underrated. It’s called laddering. You might hold a 30-year policy for the base need and a 10-year policy for the years when the kids are little and money is tightest.
Who should think twice
If you’re 30 with a newborn and a fresh 30-year mortgage a 10-year term will end right when your kids are 10. Your need won’t be gone. You’ll just be 40 and shopping again with a higher price and maybe a new health issue.
Honestly that’s the trap. People buy short because it’s cheap today. Then a diagnosis like high blood pressure or diabetes shows up later and new coverage costs far more or gets harder to get. Our guide on how much life insurance you actually need can help you size both the amount and the length.
What happens when the 10 years end
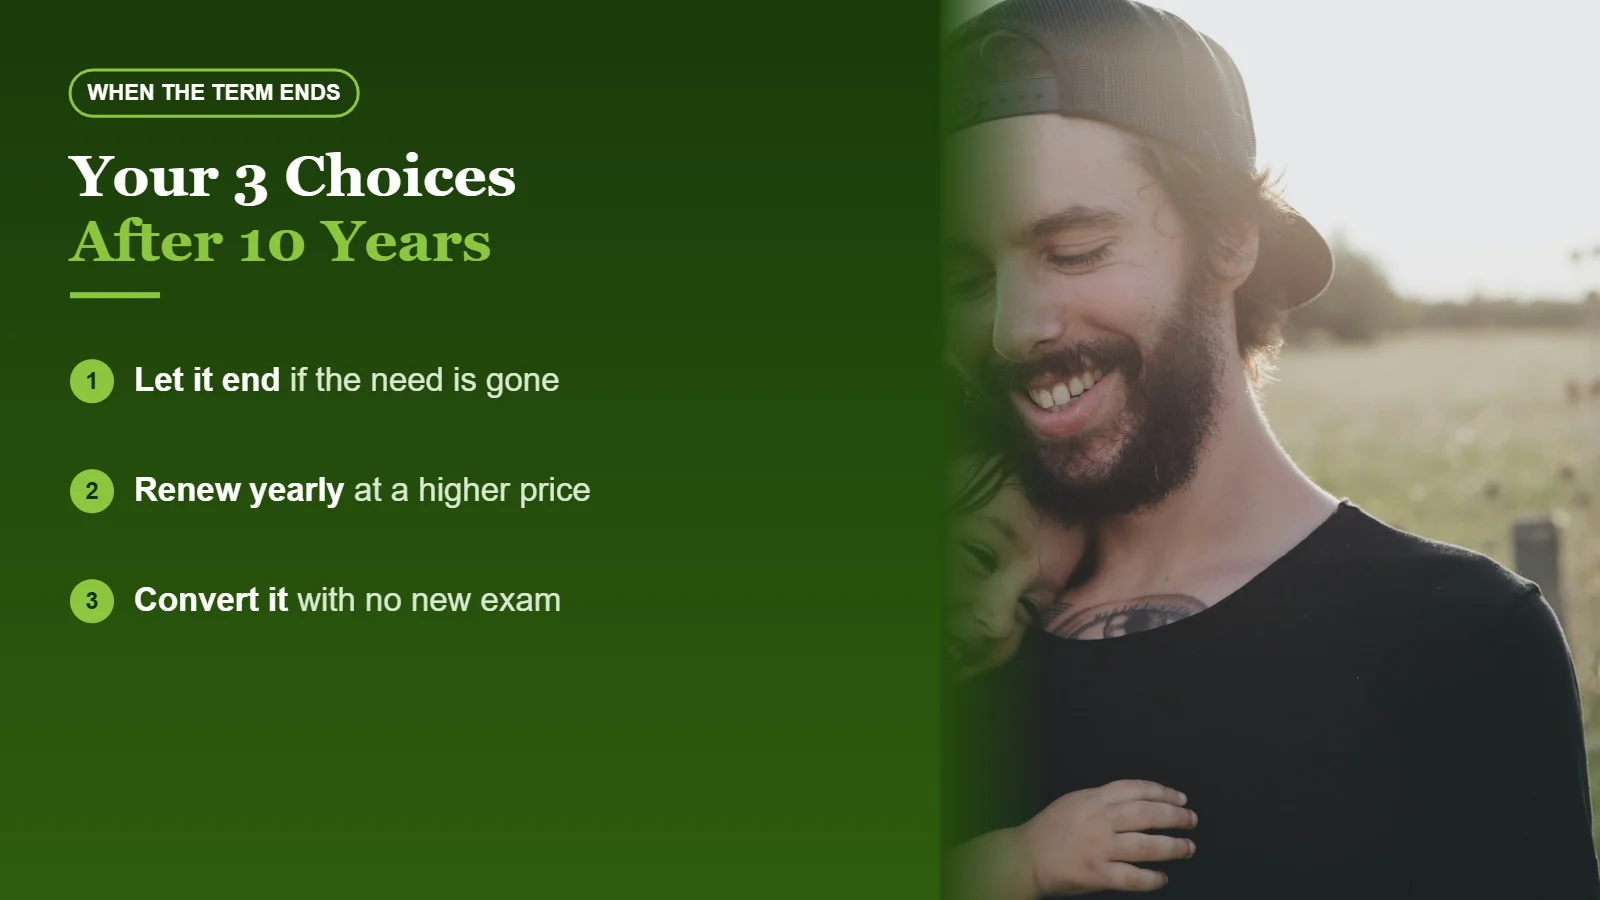
You usually have three choices.
Let it end. If your need is gone that’s fine. You paid for protection and you had it.
Renew yearly. Many policies let you keep going one year at a time. But the price resets to your current age each year. It’s usually the most expensive path over time.
Convert it. A conversion rider lets you switch to permanent coverage without a new medical exam. This is the feature that protects you if your health changes. Permanent coverage costs much more though. MoneyGeek shows a 40-year-old man paying about $41 a month for 10-year term versus several hundred dollars a month for whole life.
How to buy a 10-year term the smart way
Step 1: Write down when each big need ends. Mortgage payoff year. The year your youngest turns 18 or finishes college. The year a loan is paid. If everything ends within ten years then a 10-year term makes sense.
Step 2: Price 10 and 15 and 20 years side by side. The gap is often small. A 15-year term is a nice middle ground that many people forget exists.
Step 3: Confirm the conversion rider. Ask how long the conversion window lasts. Some close before the term ends so read the contract.
Step 4: Check the insurer. Look at financial strength with AM Best and complaint data at the NAIC. A cheap policy from a weak company isn’t a bargain.
Step 5: Consider a no-exam option if speed matters. Some insurers approve healthy applicants without a medical exam. Our guide on no medical exam life insurance explains the tradeoffs.
Real situations and what usually fits
A 52-year-old with eight years left on the mortgage. A 10-year term lines up neatly. It costs more at this age than at 35 but it covers exactly the risk that matters.
A 33-year-old couple with toddlers. A 20 or 30 year base policy usually fits better. A small 10-year layer on top can help during the most expensive childcare years.
Someone with only work coverage. Group life usually ends when you leave the job. A 10-year individual policy can fill a gap during a career change. Read our guide on group vs individual life insurance for more.
Someone over 60. Options shrink and prices rise fast. Our guide to life insurance for seniors covers what still works.
10-year term vs 20-year term: a simple way to decide
Here’s a small test I like because it takes two minutes. Picture yourself exactly ten years from today. Then answer three questions honestly.
- Would anyone still depend on my income to pay rent or a mortgage
- Would there still be a child at home or in college
- Would my savings alone cover my family if I were gone
If the first two answers are no and the third is yes then a 10-year term is probably enough. If even one answer points the other way then price a 20-year term before you decide. The extra cost per month is often less than a streaming subscription.
One more thing people rarely think about. A longer term doesn’t trap you. You can usually cancel a term policy at any time by stopping payments. So buying 20 years and dropping it at year 14 is often cheaper than buying 10 years and starting a brand new policy at an older age.
The weird part is that many people do the opposite. They pick the shortest term to feel thrifty and then pay much more later. A little planning now usually beats a rushed decision at 45.
Common mistakes
- Choosing the term only because it’s the cheapest line on the quote
- Skipping the conversion rider to save a few dollars
- Not comparing a 15-year term
- Assuming you can always buy more later at a similar price
- Forgetting to name a backup beneficiary
Frequently asked questions
Is 10-year term life insurance worth it
It’s worth it when your main financial need ends within ten years. If your need lasts longer a 20 or 30 year term is often the better value.
Can I renew a 10-year term policy
Many policies allow yearly renewal after the term. The price is based on your age at each renewal so it rises quickly.
Does a 10-year term build cash value
No. Term life only pays a death benefit. If you want savings built into a policy that’s permanent coverage and it costs far more.
Want lifelong coverage that grows cash value instead of a 10-year term? Read how using life insurance to build wealth really works before you pay more.
Final thoughts
A 10-year term isn’t a cheap shortcut and it isn’t a bad deal either. It’s a tool for a short need. Match the length to the years your family truly depends on your income and you’ll rarely regret it.
If you want to compare companies next our guide to the best life insurance in 2026 shows how to judge them.
Disclaimer: This article is general information and not advice for your exact case. Prices shown are third-party estimates and real quotes vary by age and health and insurer and state. Talk to a licensed agent before you buy.