

AI Liability Insurance for Small Business: What Your Policy Might Miss
Think about the last week at your business. Maybe you used ChatGPT to draft a client email. Maybe a chatbot answered questions on your website overnight. Maybe an AI tool wrote product descriptions or screened job applicants. It all felt like saving time. And it probably was.
But here’s a question most small business owners never ask. If that AI tool gets something wrong and a customer loses money or gets hurt or sues you for it, who pays? A lot of owners assume their current insurance covers it. Sometimes it does. Sometimes there’s a gap nobody noticed until the claim letter shows up.
This guide walks through what AI liability insurance for small business really means and where the gaps tend to hide. You’ll also see what to ask your agent before something goes wrong.
The quick answer
There isn’t one standard policy called AI insurance yet. Most AI-related risks fall under coverage you may already know. That means general liability and professional liability and cyber insurance. The problem is that some insurers now add AI exclusions or narrow wording. So the real job is checking how your current policies treat AI use and then filling any gap with an endorsement or a specialty policy.
What can actually go wrong
AI risk sounds abstract until you picture it in a normal business. Here are the kinds of problems that tend to come up.
- A chatbot gives a customer wrong pricing or wrong safety advice and they act on it
- An AI writing tool copies text or images that belong to someone else
- A hiring tool screens out applicants in a way that looks unfair
- Customer data gets pasted into an AI tool and ends up exposed
- An AI-generated report or estimate has an error a client relied on
- A fake voice or deepfake video tricks an employee into sending money
Notice that none of these need fancy technology. They come from everyday tools that millions of small businesses already use.
How your existing policies may respond
Each common policy covers a different slice of risk. Here’s how they usually line up with AI problems.
| Policy | What it usually covers | Where AI can create a gap |
|---|---|---|
| General liability | Bodily injury and property damage and some advertising injury | Financial losses from bad advice usually aren’t covered here |
| Professional liability or E&O | Mistakes in the services or advice you give clients | Some policies exclude work done mainly by software |
| Cyber insurance | Data breaches and ransomware and some fraud losses | Social engineering fraud may need a separate add-on |
| Employment practices liability | Claims of discrimination or unfair hiring | Check whether automated hiring decisions are included |
| Media liability | Copyright and trademark and defamation claims | AI-generated content may be limited or excluded |
A quick word on terms. E&O stands for errors and omissions. It’s another name for professional liability. And an exclusion is a line in your policy that says what isn’t covered.
Why exclusions are the part to watch
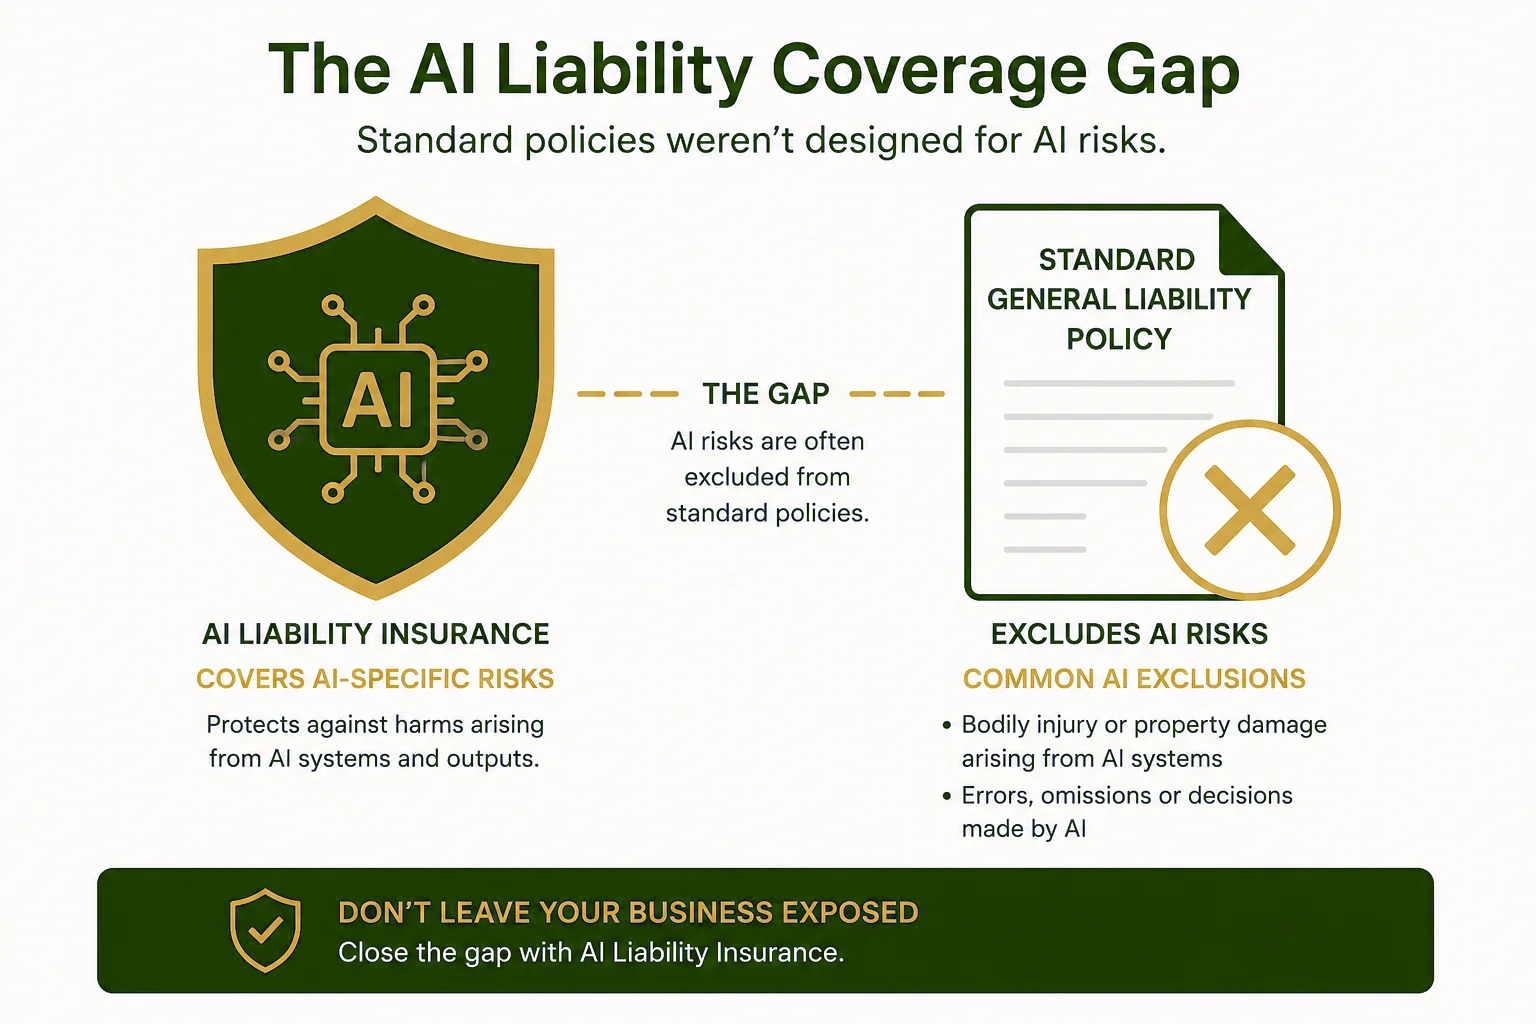
Honestly this is where the real story is. Insurers are still figuring out how to price AI risk. Some have started adding wording that limits claims tied to AI. Others are adding separate AI endorsements you can buy. Industry groups have also been drafting new standard forms that touch on AI.
That means two businesses with the same type of policy can have very different protection. The only way to know is to read your policy or ask your agent to point to the exact wording.
A hypothetical example
Picture a small marketing agency that uses an AI tool to write blog posts for clients. One post includes a paragraph that closely copies a competitor’s article. The competitor’s lawyer sends a demand letter.
The agency has general liability. But that policy may not respond to a copyright claim tied to professional work. Their professional liability policy might. Unless it has an exclusion for intellectual property. Suddenly the owner is reading three policies at once and calling an agent in a panic.
This is only an illustration. But it shows why checking before a claim beats checking after one.
How to check your coverage step by step
Step 1: List every AI tool your business uses. Include free tools that employees use on their own. You might be surprised how long the list gets.
Step 2: Write down what each tool touches. Customer data? Client deliverables? Hiring? Payments? This tells you which policy matters for each risk.
Step 3: Pull your current policies. That usually means general liability and professional liability and cyber. Search each one for words like artificial intelligence and automated and algorithm and software.
Step 4: Send your agent a short email with your AI list. Ask a direct question. If one of these tools causes a client loss, which policy responds and are there any exclusions?
Step 5: Ask about endorsements. Some insurers offer add-ons that restore coverage for AI-related errors or expand fraud coverage for deepfake scams.
Step 6: Put the answers in writing and save them with your policy files.
Simple habits that lower your risk
Insurance is the backup plan. The front line is how your team uses AI every day. These habits also make your business look better to an underwriter. An underwriter is the person at the insurer who decides whether to cover you and at what price.
- Have a human review anything AI writes before a client or customer sees it
- Never paste customer personal data into public AI tools
- Keep a short written policy on which tools employees may use
- Add a clear note on your chatbot that it can make mistakes
- Use call-back checks before sending any payment requested by email or voice
- Keep records of how AI was used on client work
That payment check matters a lot. Deepfake voice scams have become a real concern for businesses. A five-minute call to a known phone number can stop a very expensive mistake.
Which businesses should look closest
Every business using AI should do a quick check. But some face more exposure than others.
Consultants and agencies. If you sell advice or creative work then AI errors land right in professional liability territory.
Online stores. Chatbots and AI product descriptions can create pricing errors or false claims about products.
Healthcare and finance businesses. Rules are stricter and mistakes can hurt people more. Talk to an agent who knows your industry.
Any business that hires. Automated resume screening can raise discrimination questions. Federal agencies such as the EEOC have warned employers that they can be responsible for biased results from AI tools.
Where to buy coverage
Start with your current agent or broker. They already know your policies and can request endorsements. If they don’t seem familiar with AI risk then it’s fair to get a second opinion from a broker who works with tech or professional service firms.
Specialty insurers have also started offering policies built around AI errors. Read the definitions closely. What counts as an AI system in one policy may not match another.
And remember the basics still matter. If you don’t yet have the core policies in place then our guide on general liability vs professional liability insurance is a good place to start. Our article on cyber insurance for small business covers data breach protection in more detail.
Common mistakes with AI liability insurance for small business
- Assuming general liability covers every kind of lawsuit
- Waiting for the market to settle before checking your coverage
- Forgetting about free AI tools employees use on their own
- Skipping human review because the AI output looks polished
- Never asking the agent to show the exact exclusion wording
- Buying a new policy without checking how it overlaps with old ones
Frequently asked questions
Is there a specific AI insurance policy for small businesses?
A few specialty insurers offer AI-focused coverage. But most small businesses handle AI risk through existing liability and cyber policies plus endorsements where needed.
Does cyber insurance cover deepfake scams?
Sometimes. Many policies cover social engineering fraud only through an add-on with a lower limit. Ask your agent directly.
Do I need to tell my insurer I use AI?
If an application asks about it then answer honestly. Leaving out facts can cause problems with a claim later.
A calm way to finish
You don’t need to stop using AI. It’s helping a lot of small businesses work faster. You just need to know what happens if it gets something wrong. Make a list of your tools. Ask your agent one clear question. Then close any gap before it costs you.
The US Small Business Administration also has a plain guide to the main types of business insurance if you want a broader view.
Disclaimer: This article is general information and not legal or insurance advice for your business. Coverage depends on your policy wording and your state. Talk to a licensed insurance professional before you make a decision.