

6 Smart Steps to Choose Hybrid Life Insurance

Maybe it started with a parent. A fall in the kitchen and then a few weeks in rehab. Then the conversation nobody wants to have about who will help with bathing and meals and medicine. And then the bill.
A lot of families find out the hard way that regular health insurance and Medicare don’t pay for that kind of long-term help. That’s usually when someone asks if there’s a policy that covers it. And the answer these days often points to hybrid life insurance with long-term care.
This guide explains how these hybrid policies work and what care actually costs and who they make sense for. It also covers who might be better off with something else.
The quick answer
Hybrid life insurance with long-term care is a life policy that lets you use part or all of the death benefit to pay for care if you need it. If you never need care your family gets the death benefit. It can make sense for people in their 40s to 60s with savings to protect. It costs more than plain term life.
Why long-term care is such a big deal
Long-term care means help with daily life. Things like bathing and dressing and eating and getting around. It can happen at home or in assisted living or in a nursing home.
Here’s the part that surprises people. Medicare generally doesn’t pay for this kind of ongoing custodial care. Regular health insurance doesn’t either. Medicaid can help but usually only after you’ve spent down most of your savings.
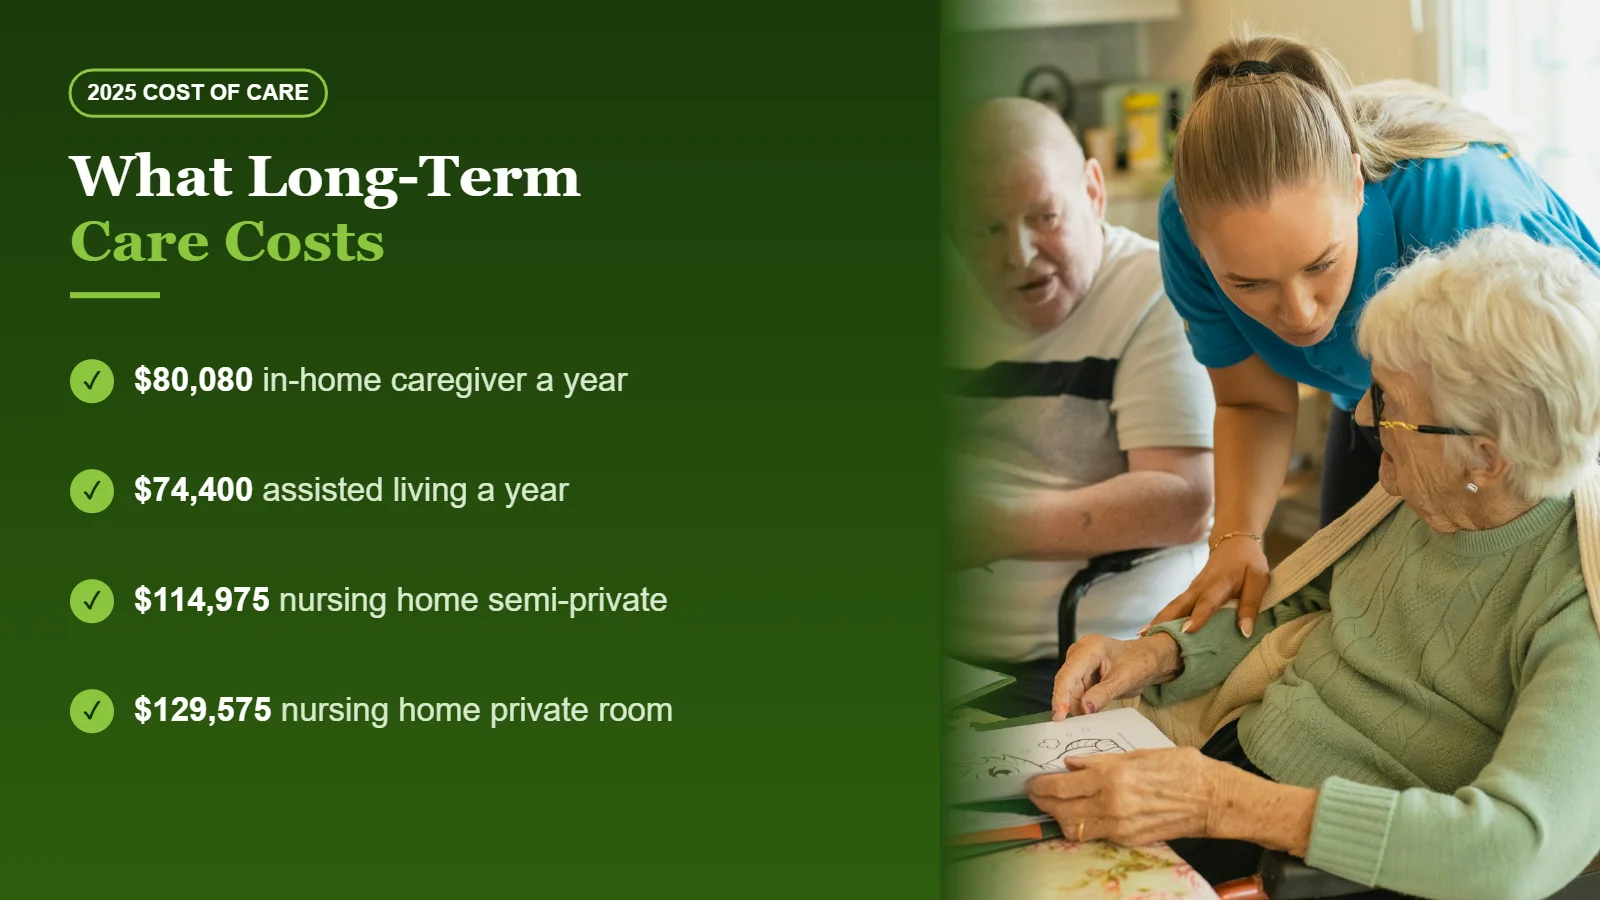
And the costs are big. CareScout’s 2025 Cost of Care Survey found these national median costs.
| Type of care | 2025 national median |
|---|---|
| In-home caregiver | $35 an hour or about $80,080 a year at 44 hours a week |
| Adult day health care | about $24,700 a year |
| Assisted living | $6,200 a month or about $74,400 a year |
| Nursing home semi-private room | about $114,975 a year |
| Nursing home private room | about $129,575 a year |
A few years of care can wipe out decades of savings. That’s the risk hybrid policies try to solve.
Why hybrid policies are growing
For years people bought standalone long-term care insurance. Then many of those policies turned out to be priced too low. Some insurers left the market and many customers faced large rate increases.
Hybrids filled the gap. A 2026 EY report done with LIMRA calls hybrid offerings the leading private long-term care solution. The same report says 63% of people express a need for insurance focused on long-term care. Industry leaders also expect hybrids to be one of the biggest life insurance trends in 2026.
How hybrid life and long-term care policies work
There are two main types. They sound similar but work differently.
A life policy with a long-term care rider. A rider is an add-on to a policy. This one lets you take part of your death benefit early to pay for care. Whatever you don’t use goes to your family when you die.
A linked-benefit policy. This is built mainly for long-term care. It often provides a pool of care money that’s larger than the death benefit. Many of these can be paid with one lump sum or over a set number of years. Some offer a return of premium option if you change your mind later.
To get care benefits you usually need to meet a trigger. Commonly that means needing help with at least two activities of daily living or having a serious cognitive problem like dementia. There’s also often a waiting period before benefits start.
The real pros
- No use it or lose it. With old-style care insurance you could pay for decades and never use it. A hybrid pays something either way
- Prices are usually more stable. Many hybrids lock in the premium. Standalone care policies often raised rates later
- Flexibility. Money can go toward home care and not just a nursing home in many policies
- Peace of mind for kids. Adult children often end up as caregivers. A plan can take some of that weight off them
The honest cons
- They cost more than term life. You’re paying for two kinds of protection
- Less care coverage per dollar. A standalone care policy may give you more care benefit for the same money
- Complicated contracts. Riders and triggers and inflation options vary a lot between companies
- Big upfront payments. Some linked-benefit plans need a large lump sum
- Underwriting. You’ll answer health questions and some people won’t qualify
Honestly the complexity is what trips most people up. Two policies with similar names can work very differently.
Who a hybrid policy often fits
- People in their 40s to early 60s who are still healthy enough to qualify
- Families with savings or a home they want to protect from care costs
- People who hate the idea of paying for insurance they might never use
- Couples who want a plan where one person’s care doesn’t drain the other’s retirement
Who might want something else
If you mainly need to replace income for young kids then plain term life is usually cheaper and simpler. Our guide on 10-year term life insurance explains that option. And if you’re not sure how much coverage you need at all start with how much life insurance you actually need.
People with very limited savings may rely on Medicaid if they ever need long-term care. Paying for a hybrid may not be the best use of tight money in that case.
A hypothetical example
Picture a healthy 55-year-old with about $300,000 saved for retirement. She watched her mother need years of home care and she doesn’t want her kids to go through that.
She buys a hybrid policy with a death benefit and a larger pool for care. At 79 she needs help at home. The policy pays monthly toward an in-home caregiver. Her retirement savings stay mostly untouched.
Now picture the other ending. She stays healthy and passes away at 88 without needing much care. Her kids receive the death benefit. Either way the money she paid wasn’t wasted.
That’s the core appeal. But she paid more than she would have for term life. That trade-off is the whole decision.
6 smart steps to choose the right hybrid life insurance
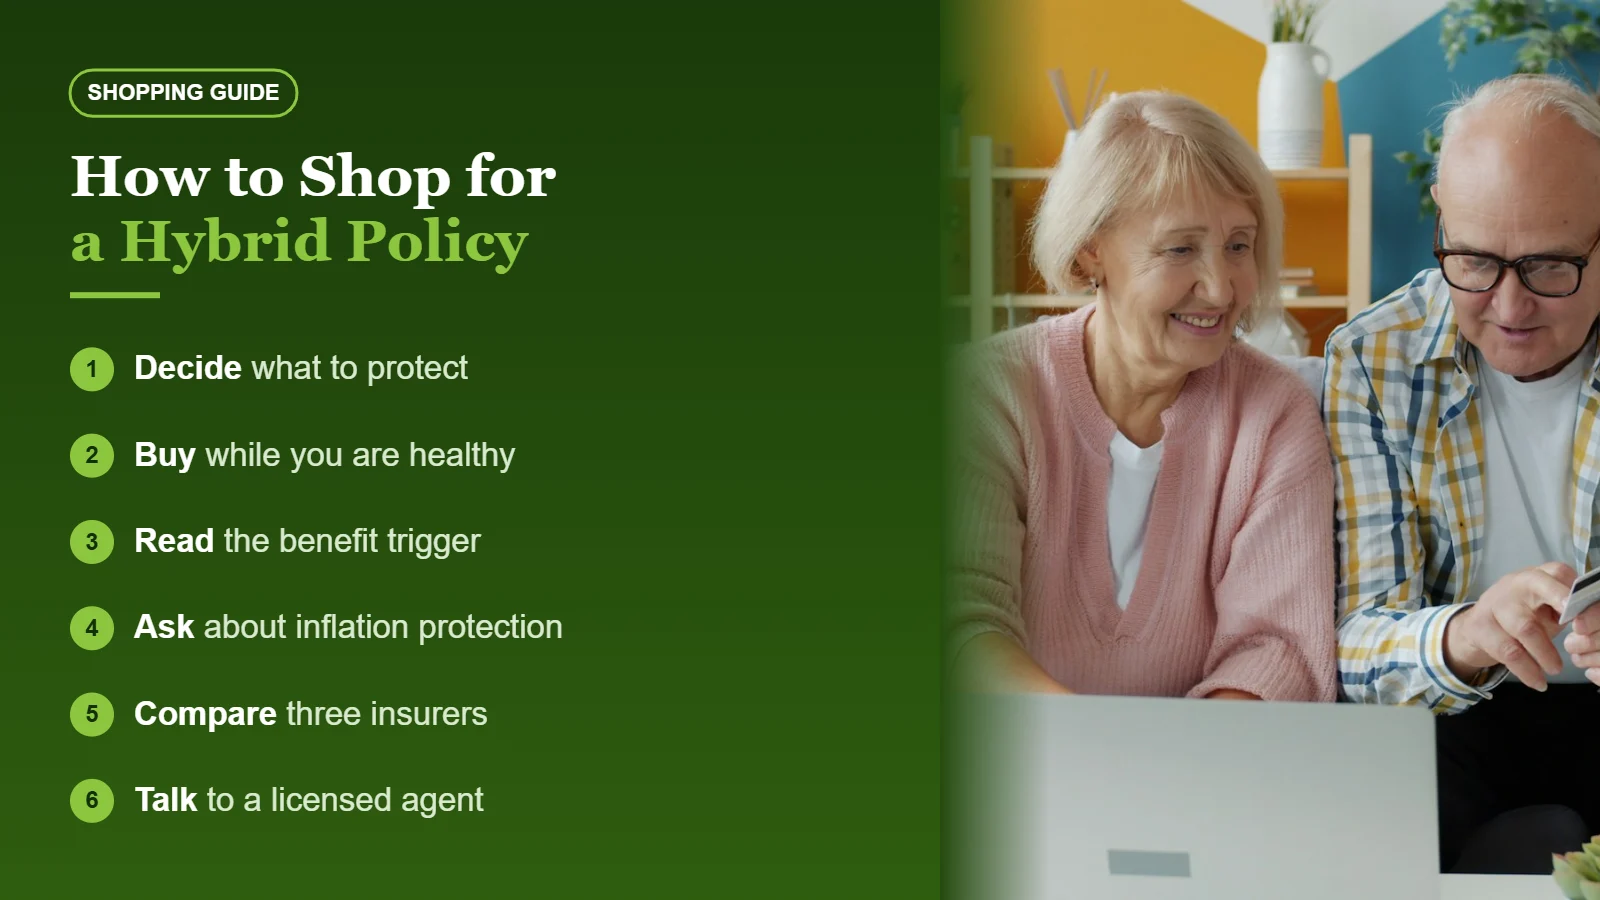
Step 1: Decide what you’re protecting. Savings and a home and your family’s time all count.
Step 2: Check your health now. Hybrids are easier to get while you’re healthy.
Step 3: Ask how benefits are triggered. Get the exact definition in writing.
Step 4: Ask about inflation protection. Care costs rise over time and a benefit that looks big today may feel small in 25 years.
Step 5: Compare at least three insurers. Look at financial strength ratings too because you may need this policy decades from now.
Step 6: Talk with a licensed agent who sells both hybrid and standalone care policies. That way you see more than one option.
Common mistakes
- Buying too late. Health problems can make you ineligible
- Skipping inflation protection. It costs more but it matters over long periods
- Not reading the benefit trigger. This decides when the policy actually pays
- Confusing a chronic illness rider with true long-term care coverage. They can work differently
- Draining your emergency fund to pay a lump sum. Keep cash for everyday surprises
Frequently asked questions
Does Medicare pay for long-term care
Generally no. Medicare covers short skilled nursing stays after a hospital visit but not ongoing custodial care.
What happens if I never need long-term care
Your beneficiaries usually receive the death benefit. Some policies also offer a return of premium option.
Is a hybrid policy better than standalone long-term care insurance
Not always. A hybrid offers more flexibility and stable prices. A standalone policy may offer more care coverage per dollar.
At what age should I consider a hybrid policy
Many people look at them in their 40s to early 60s while they’re still healthy enough to qualify for good rates.
Final thoughts
Long-term care is one of those risks people don’t like to think about. That’s exactly why it catches so many families off guard. A hybrid policy won’t be right for everyone. But for people with savings to protect it can turn a scary unknown into a plan.
If you’re curious start with one conversation with a licensed agent. Ask questions until you understand exactly when the policy pays. For more ways to use life insurance in your financial plan read our guide on using life insurance to build wealth.
Disclaimer: This article is general information and not financial or tax advice. Policies and prices vary by insurer and state and health. Talk with a licensed agent or financial professional before you buy.