

ICHRA for Small Business: 5 Steps to Decide in 2027
The renewal quote lands on the owner’s desk in early fall. The group health plan is going up again. Maybe 12%. Maybe more. And the owner does the math on what that means for raises next year and feels a knot in the stomach.
A lot of small business owners are in that exact spot right now. And many are asking about something called an ICHRA. In September 2026 federal agencies started calling it a CHOICE Arrangement. This guide explains how ICHRA for small business works in plain words and when it can beat a group plan. It also covers when it can backfire on your team.
The quick answer
An ICHRA lets you give employees a fixed monthly allowance instead of a group health plan. Employees buy their own individual coverage and you reimburse them tax free up to that amount. It gives you predictable costs. But it works best when individual plans in your area are reasonably priced and your team is comfortable shopping for coverage.
Why so many small employers are looking at this now
The numbers are pretty stark. An eHealth survey from August 2026 found that 73% of small and mid-sized employers offering group coverage are considering dropping it for 2027. Cost was the top reason. More than half said they face increases of 10% or more.
Keep in mind eHealth sells health plans so the survey has a point of view. Still the trend shows up elsewhere too. The HRA Council reported record ICHRA use with about one million Americans covered this way in 2026.
How an ICHRA works step by step
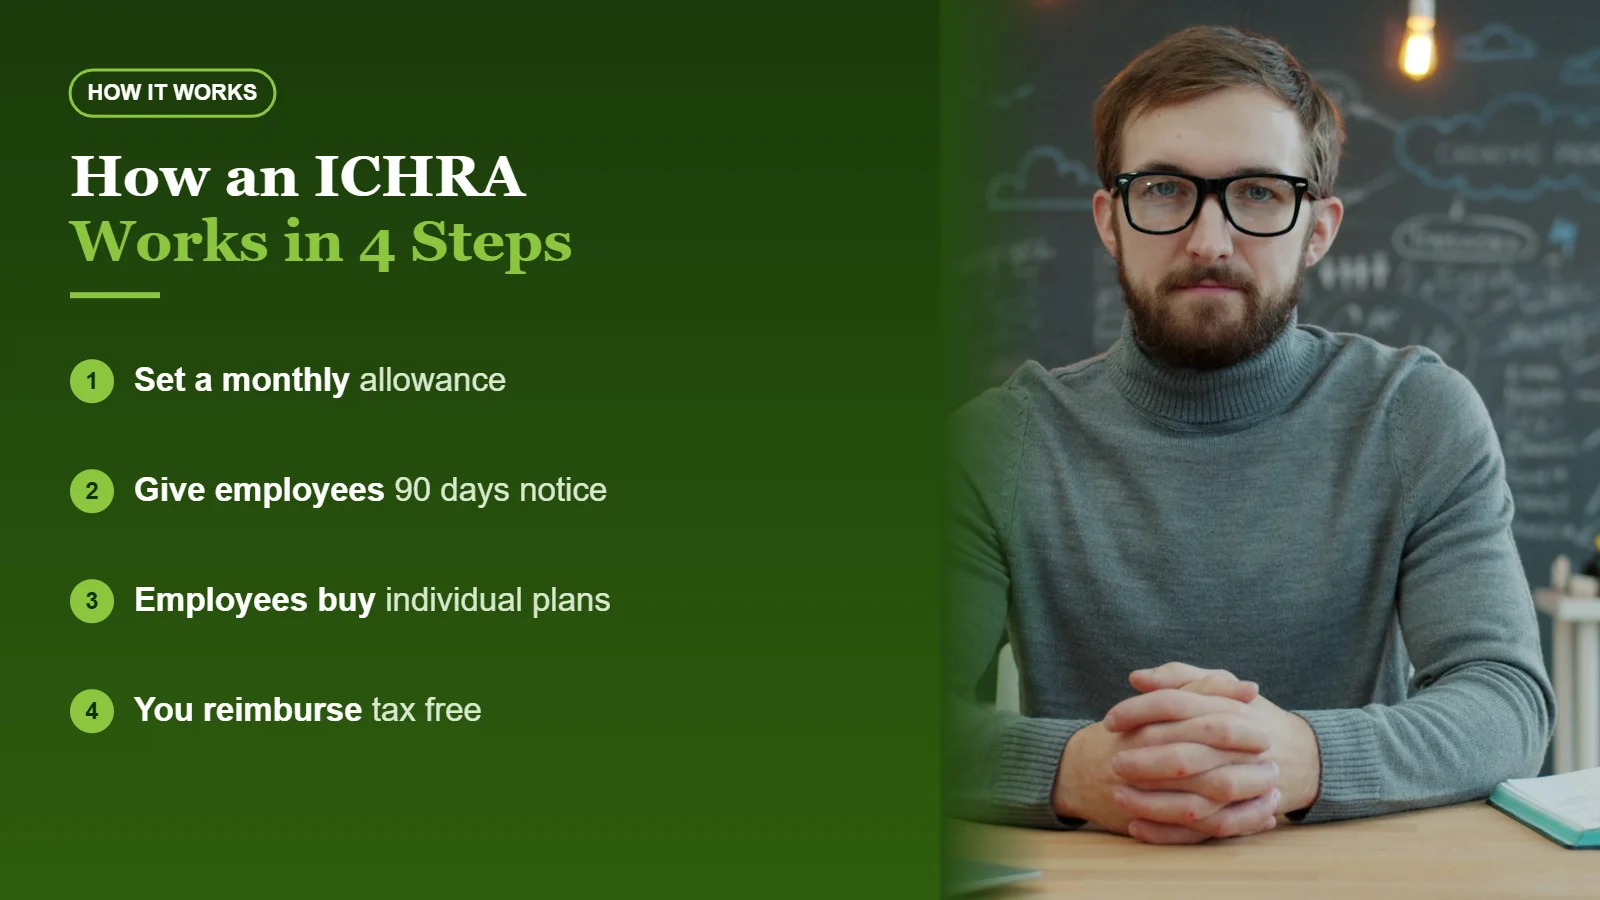
ICHRA stands for individual coverage health reimbursement arrangement. Here’s the flow in plain terms.
Step 1: You decide a monthly allowance. For example a set amount for single employees and a higher amount for employees with families.
Step 2: You give employees written notice. The rules recommend at least 90 days before the plan year starts.
Step 3: Each employee buys an individual health plan. That can be on the Marketplace or off it. Medicare Parts A and B or Medicare Advantage also count.
Step 4: Employees show proof of coverage and submit premiums. You reimburse up to the allowance and those payments are generally tax free for both of you.
Short-term plans and group plans don’t qualify. Employees need real individual coverage that meets ACA rules.
ICHRA vs group health plan
| Feature | ICHRA | Group health plan |
|---|---|---|
| Employer cost | Fixed allowance you choose | Set by insurer and can jump at renewal |
| Plan choice | Each employee picks a plan | One or a few plans for everyone |
| Portability | Employee keeps the plan after leaving | Coverage ends with the job |
| Paperwork for employees | They shop and enroll themselves | Mostly handled by the employer |
| Works across states | Yes | Often harder |
| Older employees | May pay more unless allowance varies by age | Same plan price structure for the group |
Notice the tradeoff. You get control over cost. Your employees get choice but also more homework.
The affordability rule and tax credits
This part trips people up. If you offer an ICHRA an employee can’t also get Marketplace premium tax credits when the ICHRA counts as affordable. If it’s unaffordable the employee can turn it down and use tax credits instead.
For the 2027 plan year the ICHRA is considered affordable when the employee’s cost for the lowest-cost silver plan in their area is under 10.22% of household income after your allowance. Larger employers with 50 or more full-time workers must offer affordable coverage to avoid penalties. Smaller employers don’t face that penalty but the affordability test still decides whether employees can use tax credits.
Honestly this is where a benefits advisor earns their fee. A lower-income employee may sometimes be better off with tax credits than with a small allowance.
When an ICHRA makes sense
- Your group renewal keeps jumping and you want a fixed budget
- Your team is spread across several states
- You have too few employees to get a good group rate
- Employees want different kinds of plans or some are on Medicare
- You’ve never offered health benefits and want a simple start
When it can backfire
Individual market premiums are rising too. ACA benchmark premiums are up about 13% on average for 2027 according to KFF. Some insurers are leaving the individual market in parts of the country. In a county with few choices your allowance may not buy much.
Older employees also pay more for individual plans because prices rise with age. You can vary the allowance by age within the rules. But if you set one flat amount for everyone your older staff may feel squeezed.
And some people just hate shopping for insurance. If your team expects a ready-made plan the switch can hurt morale. Our guide to ACA open enrollment 2027 shows what employees will face on the Marketplace.
5 easy steps to decide if an ICHRA fits your business
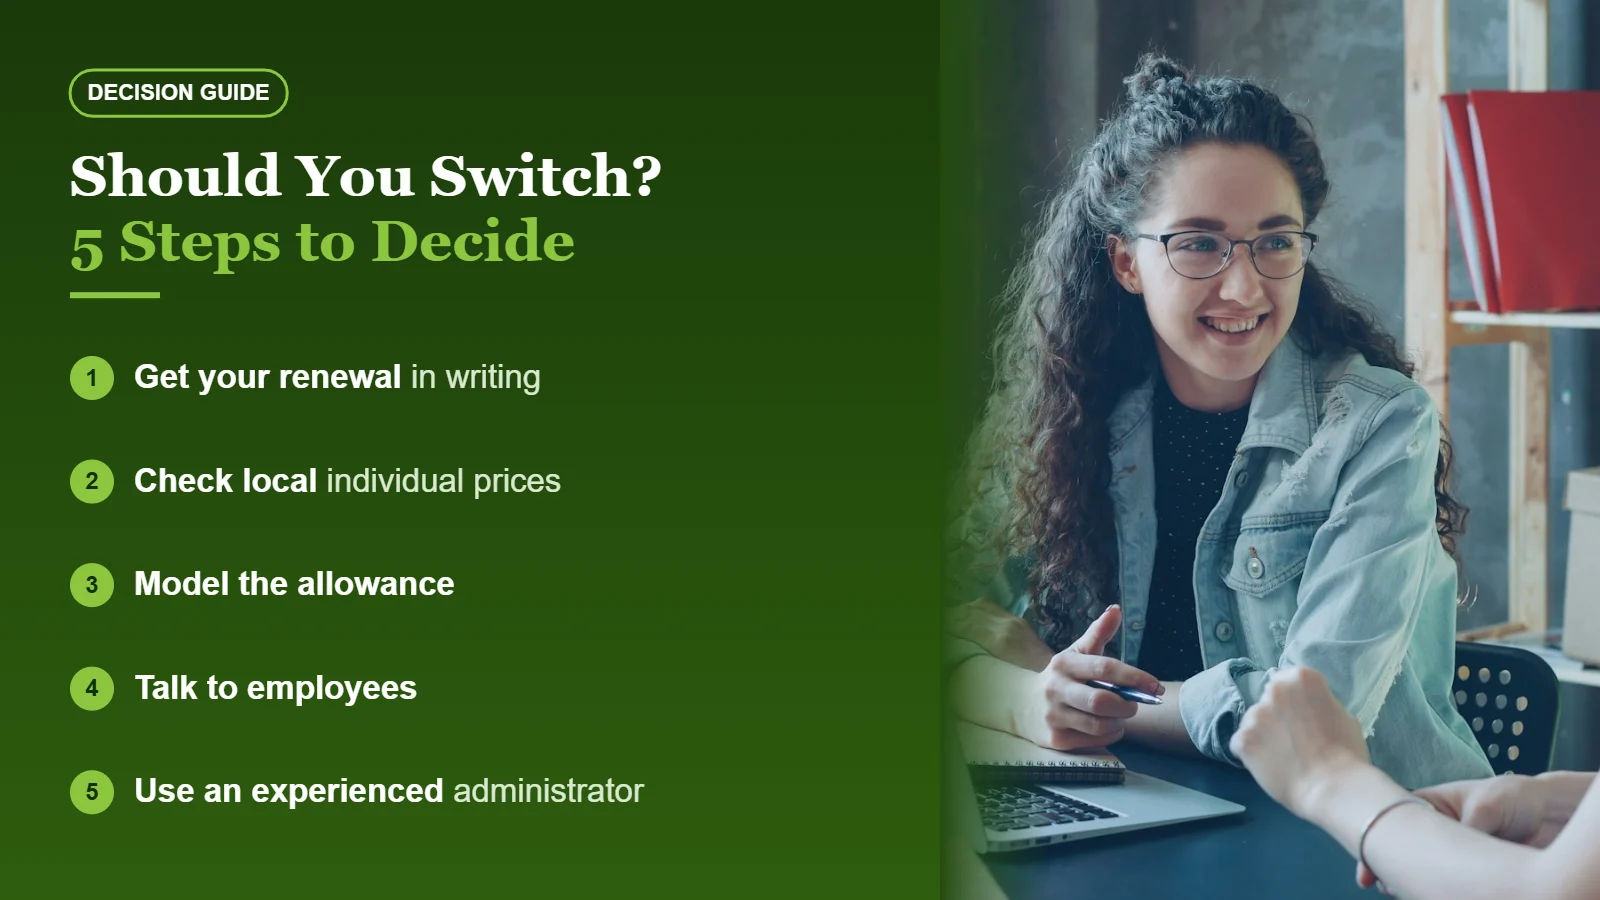
Step 1: Get your group renewal in writing. You need the real number to compare.
Step 2: Check individual plan prices for your employees’ ZIP codes. Look at HealthCare.gov or your state exchange using a few employee ages.
Step 3: Model the allowance. See whether your planned amount covers a decent silver or bronze plan for most of the team.
Step 4: Talk to employees early. Ask what they value most. Some care about a specific doctor. Others just want the lowest premium.
Step 5: Use an experienced administrator. Many brokers have never set one up. Pick someone who has and ask how they handle proof of coverage and reimbursements.
How to explain the change to your team
This is the part owners often rush. And it’s the part employees remember. A good benefit explained badly can feel like a pay cut.
Start with the why. Be honest that group costs keep rising and that a fixed allowance lets the business keep offering help with health costs. Then show real examples. Pull up two or three Marketplace plans for a typical employee and show what the allowance covers.
Give people time and support. Share the enrollment dates in writing. Offer a short session with your administrator or a licensed agent who can answer questions. And tell employees what happens if they miss a deadline so nobody ends up without coverage.
One more tip. Ask everyone to check that their doctors and medications are covered before they pick a plan. That single step prevents most of the complaints owners hear after a switch.
What about QSEHRA
Very small employers sometimes hear about a cousin of ICHRA called a QSEHRA. It’s meant for businesses with fewer than 50 full-time employees that don’t offer a group plan. The big difference is that QSEHRA has yearly reimbursement caps set by the IRS. For 2026 those caps were $6,450 for self-only and $13,100 for family coverage. ICHRA has no cap so you can be more generous if your budget allows. Ask your administrator which one fits your size and goals.
A hypothetical example
Picture a ten-person design studio with a group plan renewal up 14%. Most of the team is under 40. The owner checks local Marketplace prices and finds that a fixed allowance would cover a solid silver plan for most employees and still cost less than the renewal. Two older employees would pay more so the owner sets a higher allowance for that age group. That’s the kind of careful math that makes the switch work. Your numbers will look different.
Common mistakes
- Switching without checking local individual plan prices
- Giving employees too little notice
- Setting one flat allowance that leaves older staff behind
- Offering an ICHRA and a group plan to the same class of employees
- Forgetting to collect proof of coverage
Frequently asked questions
Is ICHRA the same as a CHOICE Arrangement
Yes. In September 2026 CMS and the SBA began using the CHOICE Arrangement name. The rules are the same ICHRA rules from 2019.
Can a very small business use ICHRA
Yes. There’s no minimum size. Even a business with one or two employees can offer one.
Are ICHRA payments taxable
Reimbursements for qualified premiums are generally tax free for employees and deductible for the business when the rules are followed.
Final thoughts
An ICHRA isn’t magic and it isn’t a trick. It’s a different way to pay for health benefits. For some small businesses it turns a scary renewal into a steady budget. For others a group plan is still the kinder choice. Run the numbers for your own team before you decide.
Health benefits are only one piece of protecting your company. Our best business insurance guide covers the rest and our article on workers’ compensation explains another must-have for employers.
Disclaimer: This article is general information and not legal or tax advice. ICHRA rules are detailed and can change. Talk to a qualified benefits advisor or tax professional before you change your health plan.