

6 Smart Ways to Handle a Wind and Hail Deductible
A hailstorm rolls through on a Tuesday night. By morning your street is full of contractors knocking on doors and your roof looks like someone hit it with a golf club. You call your insurer feeling calm. You have a $1,000 deductible after all.
Then the adjuster explains that storm damage falls under a different deductible. It’s 2% of your home’s insured value. On a $350,000 policy that’s $7,000 before insurance pays anything.
That moment is exactly why the wind and hail deductible deserves five minutes of your attention today. It’s one of the least understood lines on a home policy. And in a lot of states it’s getting bigger.
The quick answer
A wind and hail deductible is a separate deductible that applies only to damage from wind and hail. It’s usually a percentage of your dwelling coverage and not a flat dollar amount. Most fall between 1% and 5%. So a 2% deductible on a home insured for $300,000 means you pay the first $6,000 of a storm claim.
How a percentage deductible works
A deductible is the part of a claim you pay before insurance pays the rest. Most people know their regular one. It’s often $1,000 or $2,500 and it applies to things like fire or theft or a burst pipe.
A wind and hail deductible is different in two ways:
- It only applies when wind or hail causes the damage
- It’s based on your dwelling coverage which is the amount your home is insured for
Here’s how the math looks at different home values.
| Dwelling coverage | 1% deductible | 2% deductible | 5% deductible |
|---|---|---|---|
| $250,000 | $2,500 | $5,000 | $12,500 |
| $350,000 | $3,500 | $7,000 | $17,500 |
| $500,000 | $5,000 | $10,000 | $25,000 |
Notice something annoying. When your insurer raises your dwelling coverage to keep up with building costs your storm deductible grows too. Nobody sends a letter about that.
Which states feel it most
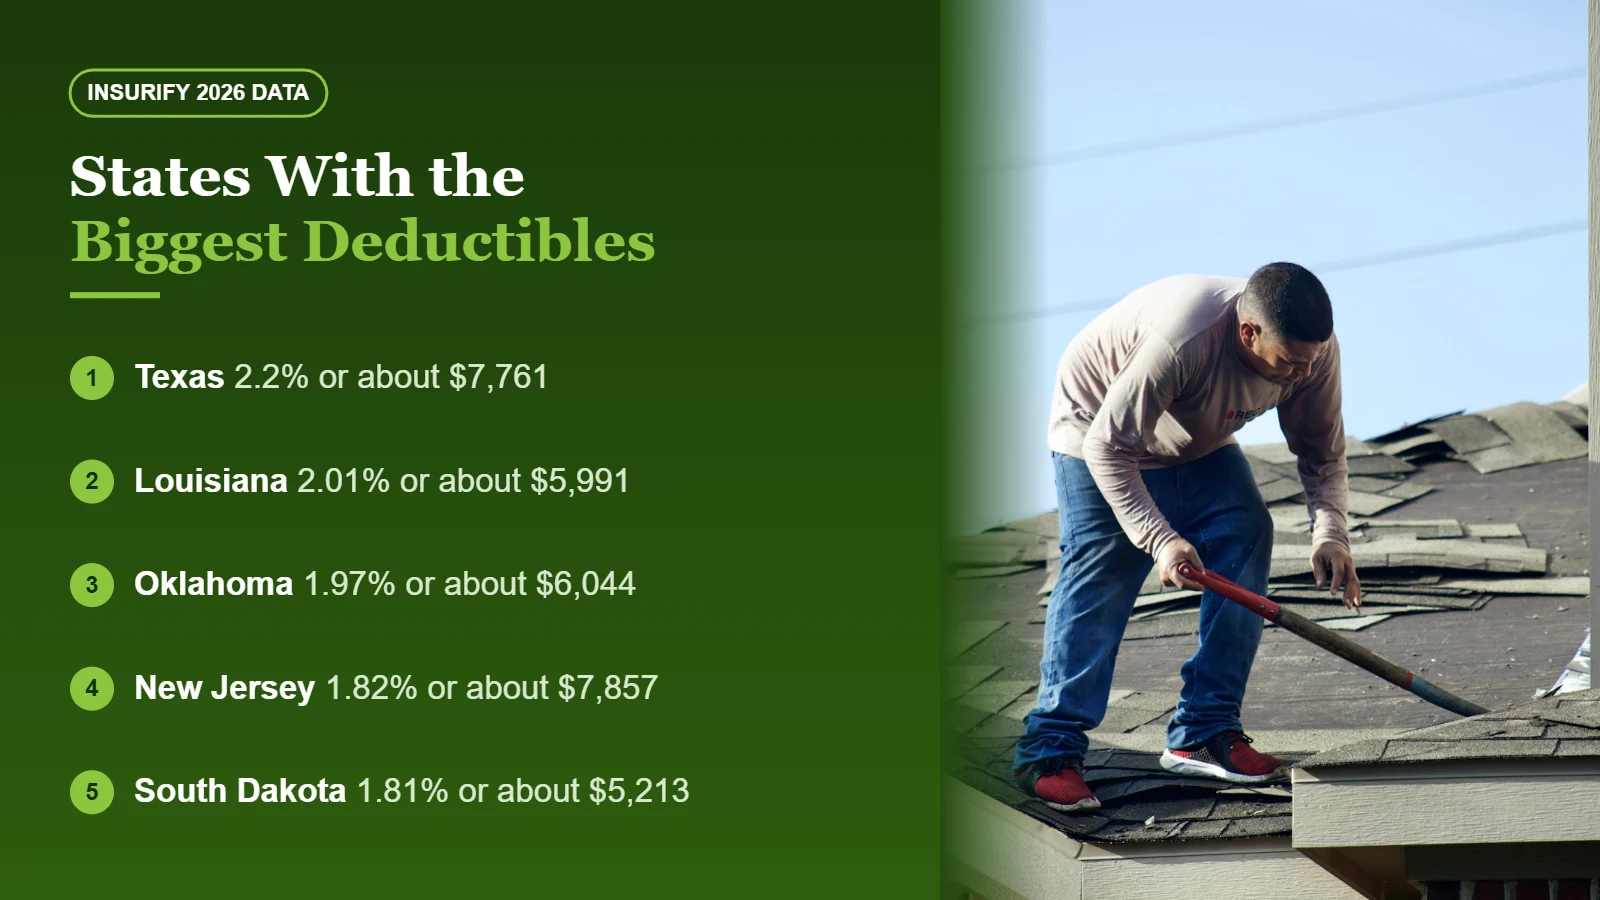
Insurify looked at average wind and hail deductibles across the country in a May 2026 report. These ten states had the heaviest burden.
| State | Average deductible | About how much in dollars |
|---|---|---|
| Texas | 2.2% | $7,761 |
| Louisiana | 2.01% | $5,991 |
| Oklahoma | 1.97% | $6,044 |
| New Jersey | 1.82% | $7,857 |
| South Dakota | 1.81% | $5,213 |
| North Carolina | 1.79% | $5,584 |
| Massachusetts | 1.73% | $7,788 |
| North Dakota | 1.53% | $4,791 |
| Nebraska | 1.45% | $5,059 |
| Kansas | 1.36% | $4,179 |
Texas stands out for a reason. It had 16.7% of all US hail events from 2023 to 2025. Hail of 2 inches or larger hit more than 235,000 Texas homes in 2025 alone.
Why insurers keep pushing these deductibles up
Hail is expensive. Insurify says it accounts for an estimated 50% to 80% of losses from severe thunderstorms. In Nebraska insurers paid $1.36 in claims for every $1 they collected in premiums over two years. That’s not a business anyone can run for long.
So insurers are shifting more of the risk to homeowners. Raising the storm deductible is quieter than raising the premium. And for many families it only shows up when they finally file a claim.
The weird part is that higher deductibles change behavior. Insurify found 10% of homeowners with storm roof damage didn’t file a claim because their deductible was too high. They just lived with the damage or paid for repairs themselves.
Hurricane deductibles are a cousin
If you live near the coast you may also see a named storm or hurricane deductible. It works the same way with a percentage of dwelling coverage. The difference is when it kicks in. It usually applies only when the National Weather Service names the storm or declares a hurricane. Each state sets its own trigger rules.
Some coastal policies have both. Read which one applies to which kind of storm. If you’re in Florida our guide on Florida home insurance rates explains what’s changing there right now.
The roof problem nobody mentions
Your deductible isn’t the only thing that shrinks a storm payout. How your roof is valued matters just as much.
With replacement cost coverage the insurer pays to replace the roof minus your deductible. With actual cash value the insurer subtracts depreciation first. That’s the wear and tear from age.
Insurify gives a clear example. A $30,000 roof replacement with a $5,000 deductible pays $25,000 under replacement cost. But if the roof is 10 years old with a 20-year lifespan then actual cash value treats it as half worn out. The payout drops to $15,000 minus the $5,000 deductible. That’s $10,000. The homeowner covers the other $20,000.
Our article on how roof age affects your home insurance goes deeper on this.
How to find your wind and hail deductible in 5 steps
This takes ten minutes. Grab your policy declarations page. That’s the summary page at the front of your policy.
Step 1: Find the section called deductibles. You may see All Other Perils and Wind or Hail listed separately.
Step 2: If the wind or hail line shows a percentage then multiply it by your dwelling coverage which is often called Coverage A.
Step 3: Write that dollar number down somewhere you’ll see it.
Step 4: Check whether your roof is covered at replacement cost or actual cash value. Look for a roof surfacing endorsement or a roof payment schedule.
Step 5: Ask yourself honestly if you could pay that amount next week. If not then it’s time to make a plan.
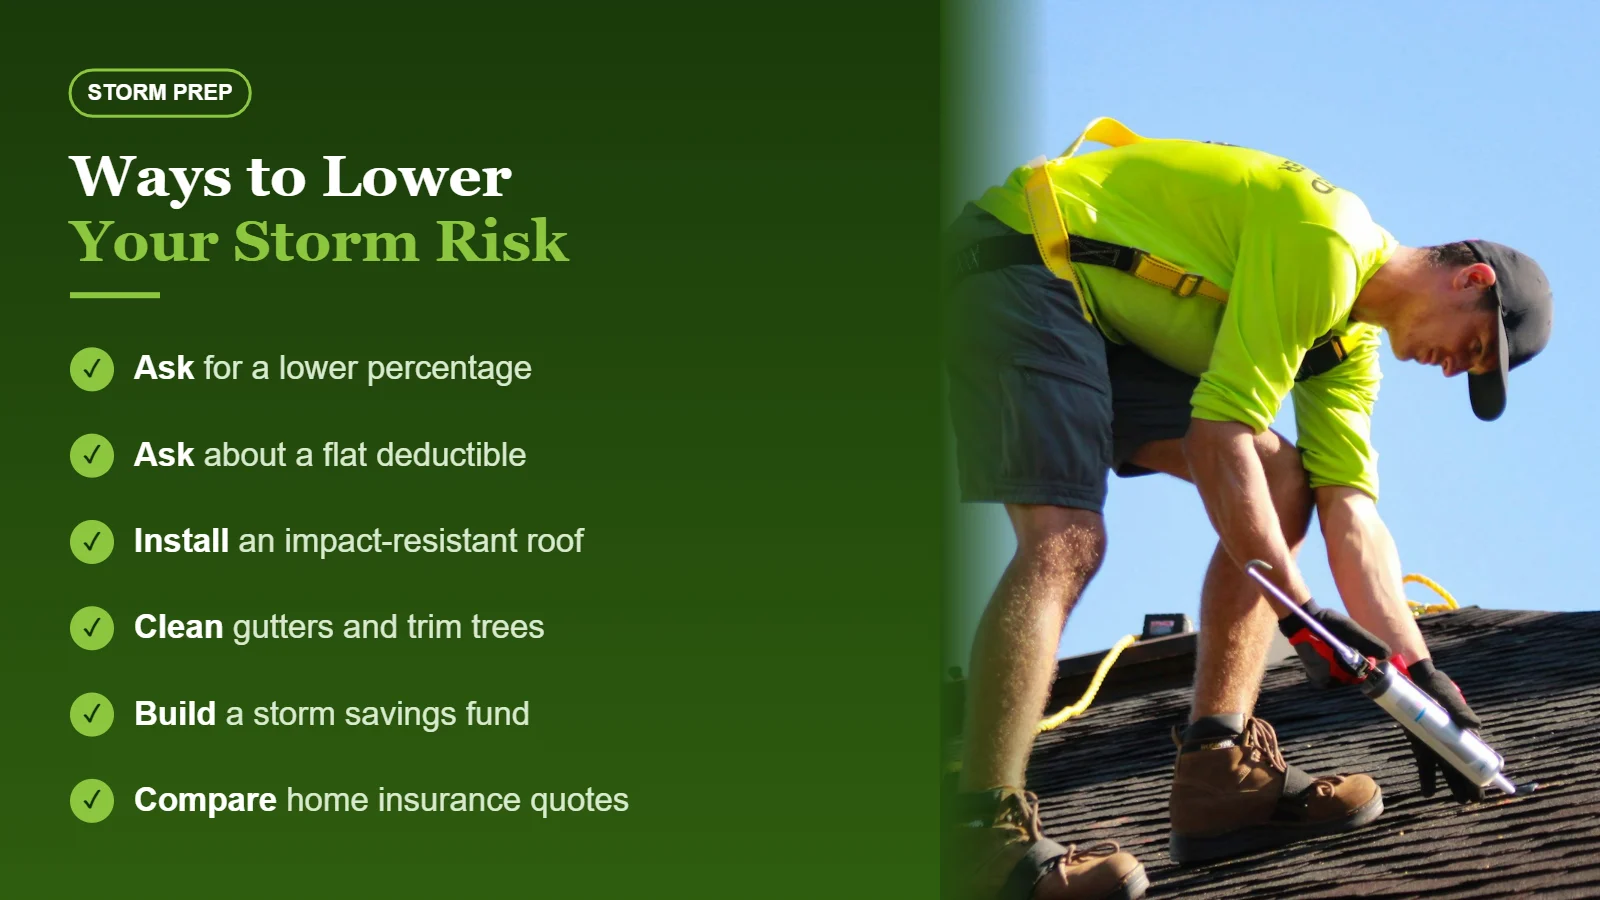
6 smart ways to lower your storm deductible costs
You have more options than you might think.
- Way 1: Ask for a lower percentage. A 1% deductible costs more in premium than 2%. Get both quotes and see the real difference
- Way 2: Ask about a flat dollar option. Some insurers still offer a fixed storm deductible in certain areas
- Way 3: Install an impact-resistant roof. Many insurers give discounts for Class 4 shingles and some states require insurers to offer them
- Way 4: Do the boring maintenance. Clear gutters and trim dead branches and tie down outdoor furniture before storm season
- Way 5: Build a storm fund. Put a little aside each month in a separate savings account until it matches your deductible
- Way 6: Compare quotes. Insurers use different rating factors. Our guide to bundling home and auto insurance shows another way to trim cost
A hypothetical example
Picture two neighbors on the same street in Oklahoma. Same size house and same builder. Both homes are insured for $300,000.
The first neighbor has a 1% wind and hail deductible and pays a little more each year for it. The second chose 2% to save on the premium.
A spring hailstorm damages both roofs. The repair estimate is $14,000 for each house.
The first neighbor pays $3,000 and insurance covers $11,000. The second neighbor pays $6,000 and insurance covers $8,000. Same storm and same damage. A $3,000 difference that came down to one checkbox at renewal.
Was the second neighbor wrong? Not necessarily. If she saved a few hundred dollars a year for many years without a storm then the lower premium may have paid off. The point is to make that choice on purpose. Not by accident.
Common mistakes homeowners make
- Assuming one deductible covers everything. It often doesn’t
- Forgetting the deductible grows. Higher dwelling coverage means a bigger percentage deductible
- Signing a contractor deal too fast. Get the adjuster out first and read any contract carefully
- Skipping photos. Take pictures of your roof and siding before storm season so you can show what changed
- Waiting to file. Many policies have deadlines for reporting damage
Frequently asked questions
Is a wind and hail deductible the same as a hurricane deductible
No. A hurricane or named storm deductible usually applies only to declared storms. A wind and hail deductible can apply to any windstorm or hailstorm.
Can I remove the wind and hail deductible
Sometimes you can switch to a flat deductible or a lower percentage for a higher premium. It depends on your insurer and state.
Does the deductible apply per storm or per year
Usually per storm or per occurrence. Two separate storms can mean two deductibles.
Will filing a hail claim raise my premium
It can. But a weather claim is generally treated differently from a claim caused by neglect. Ask your insurer how they handle it.
Final thoughts
Most people find their wind and hail deductible at the worst possible time. Standing on the driveway looking at a damaged roof. You can skip that moment by checking now while the sky is clear.
If the number scares you then you’ve learned something useful. Shop around or adjust the deductible or start a storm fund. Any of those beats being surprised.
Disclaimer: Rates and deductible rules change by state and insurer. This article is general information. Check your policy and talk to a licensed agent or your state insurance department before you make changes.